Seven links make up the chain that carries a property investor toward lasting success: defined objectives, a sound financial base, market research, diversification, steady operations, adaptability, and a planned exit.
Each link supports the next, and the investor who builds all seven is positioned for sustained success.
I have spent ten years as an industry professional, guiding clients as they assemble substantial property portfolios, and one pattern has held throughout. Durable wealth seldom grows out of casual optimism or from following whatever is trending. It grows out of a structured, long-term investment strategy, and it demands patience, discipline, and skilled execution. That is true whether the person is buying a first property, scaling up a portfolio already in hand, or arranging assets ahead of retirement. All three need a plan that screens out market noise and points toward financial independence.
Start with the destination. Before an investor scrolls through a single listing or approaches a lender, one question has to be settled: what must the portfolio deliver? Predictable passive income is one answer. Equity that accumulates over time is another, and so is commercial real estate financing to fund a corporate venture. Whichever is chosen, it steers every decision that follows.
Two more variables come next, timeline and temperament. A person working with a five-year horizon will act differently from one planning thirty years of accumulation. Risk appetite counts too, since it determines whether the investor leans toward stable residential properties or toward commercial deals that pay more but carry more risk. Specific milestones turn vague hopes into targets that can be pursued. Reaching three thousand dollars per month in net rental income within seven years is one example.
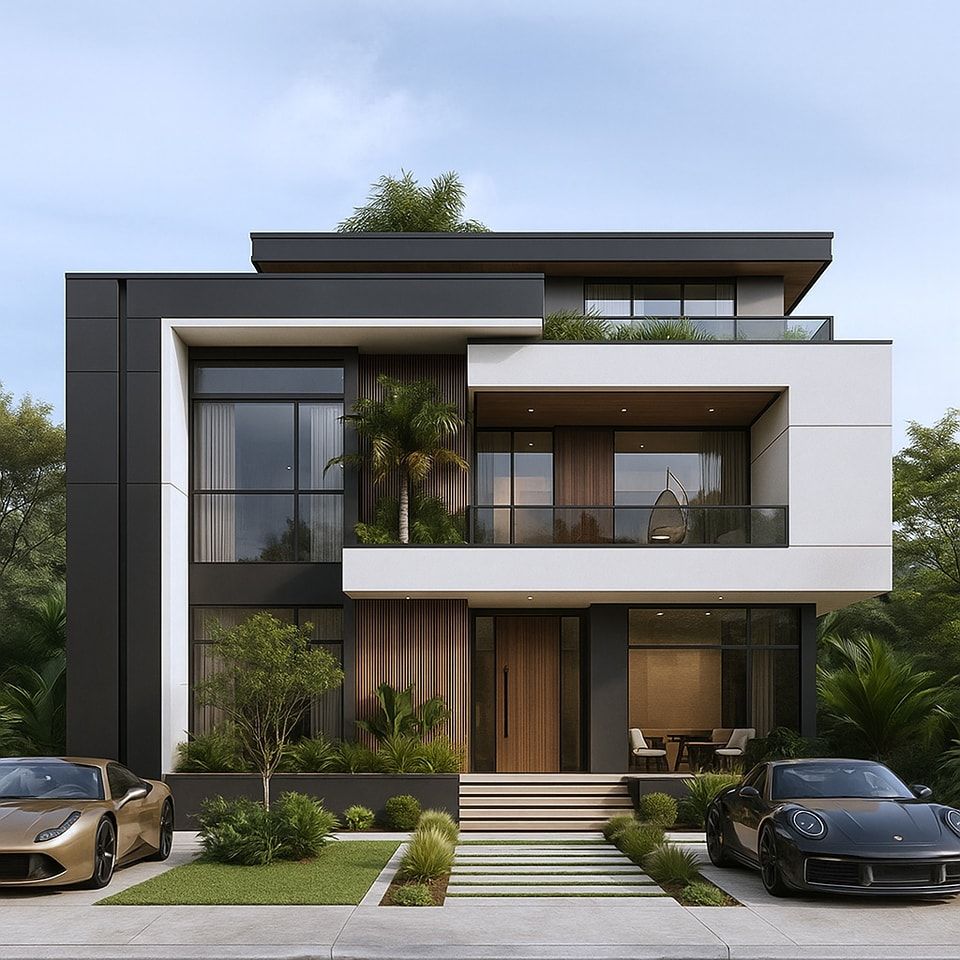
Money is the next layer, because a brilliant strategy falls apart when the finances beneath it are misaligned. Before committing capital, an investor should audit his or her personal balance sheet, including liquid savings, recurring income streams, and existing debt obligations. Lenders scrutinize those identical figures, and the picture they paint decides which mortgage rates and commercial real estate loans are within reach.
A detailed operating budget is non-negotiable. It needs to cover upfront costs, namely down payments, closing costs, inspection fees, and legal charges. It also needs a cash reserve for possible vacancies or emergency repairs. Credit deserves active attention as well. A score above seven hundred unlocks significantly better financing terms and lowers borrowing costs over the long run. A qualified financial advisor can help ensure that purchases fit smoothly within broader wealth management goals.
With goals and finances settled, the work moves outward to the market, where information works like currency. Conditions differ from place to place and shift with economic changes, population growth, and infrastructure projects. Successful investors therefore dig into regional data before deploying any capital. Neighborhood trends offer clues, and sustained job growth, expanding school districts, and new commercial development all point to promise. Supply and demand ultimately drive appreciation. Where housing inventory is limited and residents keep arriving, pressure builds upward on home values and rental yields alike. Checking employment figures, inflation trends, and regional economic forecasts on a regular basis shows whether the target market has the economic resilience to last.
Once capital is ready, concentration becomes the next danger. Spreading funds across several asset classes and geographic regions protects wealth from downturns that strike a single locality. Rather than leaning only on single-family suburban homes, an investor can blend residential real estate, multi-family units, and commercial spaces. Holdings in different places cushion the whole portfolio if one city or state hits an economic slowdown. A buy-and-hold rental approach combined with selective fix-and-flip projects balances Immediate liquidity needs against long-term capital appreciation.
Owning property is an active operating business, though. Profitability across the years depends on the quality of management and on the physical condition of the assets. Owners must decide between handling the properties personally and partnering with a professional property management firm. Doing it yourself saves administrative fees, but it consumes substantial time through tenant relations, emergency repairs, and compliance regulations. For investors with multiple units, or for those who want a truly passive experience, a reputable management company justifies its percentage fee. Whichever route is taken, routine property inspections and a proactive maintenance budget keep minor problems from turning into expensive capital expenditures. That budget should reserve roughly one to two percent of the property value each year.
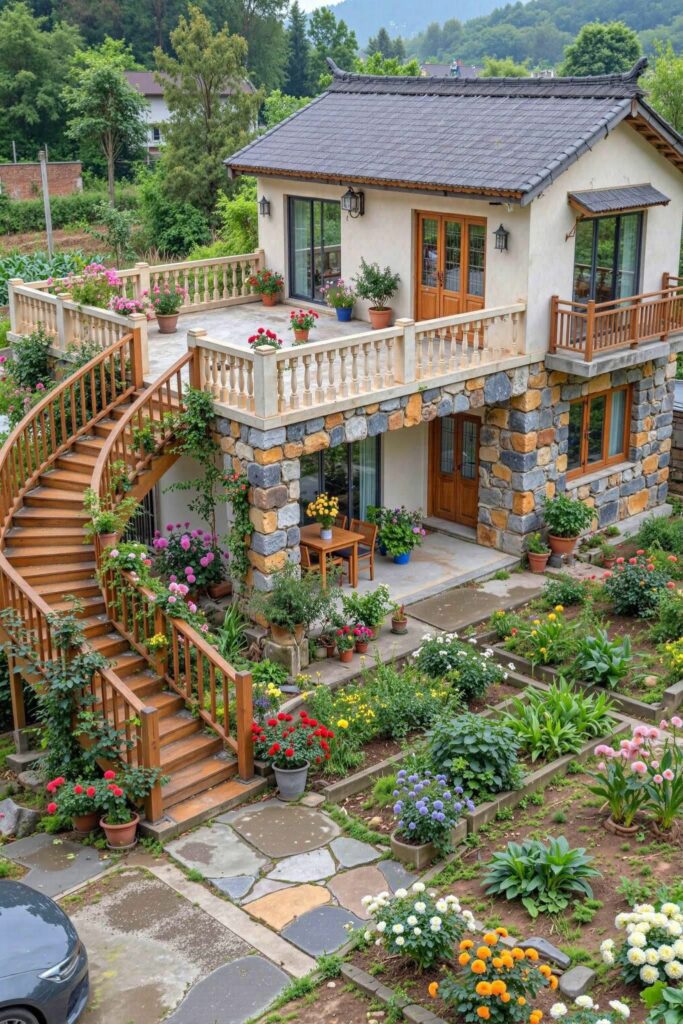
The market itself never holds still. Regulatory updates, economic cycles, and changing consumer preferences constantly reshape it, and complacency is the primary enemy of long-term success. Industry publications, networking events, and ongoing market analysis keep an investor informed and competitive. Adaptability is what keeps a portfolio resilient, whether that means adjusting acquisition criteria as mortgage rates fluctuate or pivoting toward sustainable, energy-efficient housing developments.
Finally, there is the matter of how the journey ends. An entry plan with no exit strategy is incomplete, and knowing how and when to liquidate or transition assets carries as much weight as the original purchase. One exit is selling at a market peak to maximize capital gains. Another is a tax-deferred exchange to acquire larger commercial assets, and a third is refinancing to pull out equity for the next venture. Investors focused on generational wealth transfer should build a clear estate plan with legal and tax professionals, which minimizes tax liabilities and ensures a smooth transition of assets to heirs.
For anyone ready to structure a long-term strategy, professional guidance tailored to individual financial goals is available through a personalized portfolio consultation.
Objectives, finances, research, diversification, operations, adaptation, and an exit all connect, and the strength of the whole depends on every link being in place. Which of those links would your own plan need to build first?
If this breakdown gave you something useful, tap subscribe so the next one finds you. A like helps the video reach more people, and switching on the notification bell means the latest updates arrive the moment they go live.”