Renting vs Buying a Home: Is Now the Right Time to Make Your Move?
Navigating the timeless dilemma of renting versus buying a home is a milestone that tests both your financial preparedness and your lifestyle priorities. Having spent a decade in the real estate trenches advising families, first-time home buyers, and seasoned investors, I have seen market cycles swing wildly. Clients constantly ask me whether they should keep paying a landlord or lock down a property purchase. The truth is that there is no universal answer, but with current 2025 housing market trends, interest rate shifts, and evolving economic pressures, the calculus requires a fresh perspective. Let us break down the realities of renting versus buying so you can determine the smartest path forward.
The Case for Renting: Freedom and Flexibility
While society often glorifies homeownership as the ultimate adult achievement, renting carries distinct strategic advantages that should not be overlooked, particularly in an unpredictable economic climate.
Superior Financial Agility
Choosing to lease a property grants you immense financial flexibility. You bypass the grueling task of hoarding a massive down payment, and you avoid the immediate, heavy capital outlays required for property taxes, homeowners insurance, and upfront closing fees. This liquidity means you can deploy your cash into other high-yield investments or keep a robust emergency fund intact, positioning yourself to seize unexpected opportunities instantly.
Minimized Maintenance Burdens
One of the most liberating aspects of renting is offloading property upkeep. When a pipe bursts, the HVAC system fails, or the roof develops a leak during a heavy storm, the financial and logistical burden falls squarely on the landlord. Over a decade of property management experience has shown me how unexpected repairs can decimate a homeowner’s savings overnight. Renters bypass these surprise expenses entirely, preserving both their sanity and their monthly budget.
Effortless Mobility
If your career requires frequent relocations, or if your personal life is in a phase of rapid transition, renting is unmatched. Packing up and moving at the end of a lease term is infinitely simpler and less expensive than listing a property, paying real estate commissions, and waiting months for a home sale to close. This adaptability protects you against the friction of sudden job changes or lifestyle evolutions.
The Benefits of Buying: Wealth and Stability
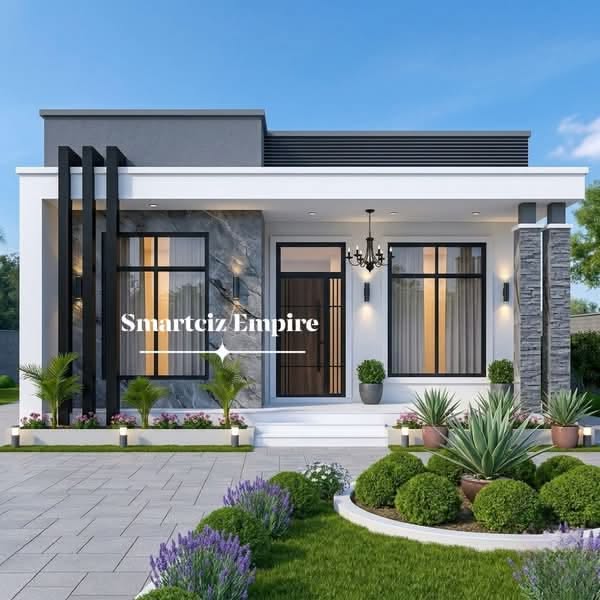
On the flip side, purchasing real estate remains a powerful vehicle for long-term wealth creation and personal security, provided your finances are properly aligned.
Building Equity and Net Worth
When you secure a mortgage and buy a home, every monthly payment acts as a forced savings plan. Instead of lining a landlord’s pockets, a portion of your hard-earned money chips away at your principal balance, building real estate equity. Over years of consistent ownership, this equity transforms into a cornerstone of your net worth.
Absolute Autonomy and Stability
Owning your property eliminates the anxiety of sudden rent hikes or a landlord abruptly deciding to sell the building. You gain total control over your living space. Whether you want to paint the walls your favorite color, completely renovate the kitchen, or adopt multiple pets, your property rules are entirely up to you.
Capitalizing on Long-Term Property Appreciation
Historically, the New Zealand property market has demonstrated robust long-term growth. Real estate values tend to appreciate over extended horizons, turning a primary residence into both a stable shelter and a compounding investment asset that hedges against inflation.
Is Now the Right Time to Buy a House?
Evaluating whether to transition from tenant to homeowner requires a cold, objective look at several critical metrics rather than succumbing to market FOMO.
Assessing Financial Stability and Readiness
Before diving into the property market, you must evaluate your financial foundation. Do you maintain a stable income stream? Is your credit score in a healthy tier to qualify for competitive mortgage interest rates? Can you comfortably service a monthly home loan payment alongside your other living expenses without living paycheck to paycheck? If your financial house is in order, purchasing a home becomes a viable pursuit.
Reading Market Conditions
Local market dynamics dictate your purchasing power. In a buyer’s market characterized by ample inventory, you enjoy more negotiating leverage, inspection contingencies, and potentially seller concessions. Conversely, a seller’s market brings fierce competition and elevated price tags. Monitoring local housing inventory and consulting a trusted real estate professional will clarify where your local market currently stands.
Aligning with Long-Term Horizon Goals
Real estate is an illiquid asset that requires a multi-year commitment to offset transaction costs. If you anticipate staying put in the same region for at least five to seven years, buying makes profound financial sense. If your professional trajectory or personal life remains volatile, maintaining the flexibility of a rental agreement is usually the wiser play.
Down Payment Strategies and Affordability
Accumulating a 20% down payment remains the gold standard because it eliminates lenders mortgage insurance (LMI) and secures better loan terms. However, various government grants and low-deposit mortgage options exist for buyers who cannot wait. If you opt for a lower down payment, ensure you model out the total cost of borrowing so you do not stretch your monthly cash flow to a breaking point.
Factoring in Maintenance and Upkeep Costs
Homeownership demands ongoing financial vigilance. Beyond your mortgage, property taxes, and insurance, you must budget roughly 1% to 2% of the home’s value annually for maintenance and repairs. If you lack the stomach for DIY projects or prefer predictable monthly housing expenses, look toward low-maintenance options like modern townhouses or newly constructed builds.
Making Your Ultimate Decision
Deciding between renting and buying is deeply personal, hinging entirely on your unique financial ecosystem and life aspirations. There is no universal blueprint; what works brilliantly for your peers might spell disaster for your budget. Take the time to audit your finances, project your long-term plans, and analyze current housing market trends objectively.
If you find yourself at a crossroads and want absolute clarity tailored to your specific financial situation, let us connect. Schedule a consultation with our expert advisory team today to review your options, run the numbers, and take the definitive next step toward securing your housing future with absolute confidence.