Beyond the Polestar U.S. Sales Ban: The Geopolitics of Connected Cars and the Brand’s European Pivot
The American chapter for one of the auto industry’s most highly anticipated electric vehicle startups is officially closing. Following the recent implementation of the Department of Commerce’s sweeping new regulations, the much-discussed Polestar U.S. sales ban has moved from a looming geopolitical threat to an unavoidable reality. The Swedish EV maker, heavily backed by its Chinese parent company, has formally announced it will not appeal the ruling. Instead, the company is packing up its stateside ambitions, winding down its localized operations, and pivoting its strategic focus entirely toward its home continent.
Having spent the last decade analyzing automotive trade policies, connected vehicle technologies, and global EV market dynamics, I can confidently say that the Polestar U.S. sales ban is not just a localized corporate setback. It is a watershed moment for the global automotive industry. This decision marks a fundamental, irreversible shift in how the United States regulates foreign technology on its roads, effectively drawing a hard line in the sand regarding software architecture, data security, and international ownership structures.
The Catalyst: Unpacking the Connected Vehicle Rule
To truly understand the mechanics of how we arrived at the Polestar U.S. sales ban, we must examine the regulatory machinery that forced it. For years, the global auto industry has been aggressively transitioning toward software-defined vehicles. Today’s cars are essentially rolling supercomputers, relying heavily on telematics, V2X (Vehicle-to-Everything) communication, over-the-air updates, and continuous cloud connectivity to function safely and efficiently.
The U.S. Department of Commerce recognized the inherent vulnerabilities in this technological shift and finalized the Connected Vehicle Rule to address mounting national security concerns. The legislation specifically restricts the import and sale of vehicles featuring internet-connected technology linked to adversarial nations, primarily China and Russia. It targets the software that controls everything from cellular modules to Wi-Fi, Bluetooth, and advanced GPS tracking systems. The government’s rationale is straightforward and unyielding: vehicles equipped with foreign-controlled connected hardware and software could potentially collect sensitive national infrastructure data, track citizen movements, or, in a worst-case scenario, be manipulated or disabled remotely.
Because of its deep-rooted Geely ownership, Polestar fell directly into the crosshairs of this legislation. Despite the fact that the company operates out of a design and engineering headquarters in Gothenburg, Sweden, its majority stakeholder is the China-based Geely Holding Group. Regulatory investigators determined that this corporate structure presented a “sufficient nexus” to China. Consequently, the Polestar U.S. sales ban prohibits the brand from marketing or selling new vehicles equipped with covered software starting with the 2027 model year. Furthermore, a secondary phase of the legislation outlaws the importation of associated hardware by 2030. This swift regulatory action highlights how connected car security regulations are rapidly superseding traditional metrics of automotive manufacturing origin.
The Volvo Exemption and the Volvo Polestar Split
One of the most fascinating and highly scrutinized aspects of the Polestar U.S. sales ban is how it sharply contrasts with the fate of its immediate corporate sibling. Volvo Cars, which is also majority-owned by Geely, managed to secure an official exemption from the very same Department of Commerce rule just weeks before Polestar’s denial was finalized. How did one brand survive the regulatory gauntlet while the other was effectively exiled?
The answer lies in the nuances of corporate governance and localized software architecture. Following what was described as “significant dialogue” with federal officials, Volvo was able to demonstrate a much more independent executive management structure and a highly localized North American manufacturing and software footprint. They proved, to the satisfaction of the U.S. government, that their critical data systems and connected car platforms were sufficiently insulated from their parent company’s Chinese operations.
In stark contrast, Polestar’s underlying technology stack is much more tightly integrated with Geely’s shared global EV platforms. Even though the brand famously utilizes Google’s Android Automotive operating system for its user interface, the underlying vehicle architecture and core control structures could not definitively pass the government’s stringent security audits. This regulatory divergence effectively cements the Volvo Polestar split, proving that U.S. regulators are now looking far past the exterior sheet metal and heavily scrutinizing the source code. The Polestar U.S. sales ban confirms that the “nationality” of a vehicle is no longer determined by where its chassis is assembled, but by who ultimately controls its software updates and data telemetry.
Supply Chains and the Illusion of Local Assembly
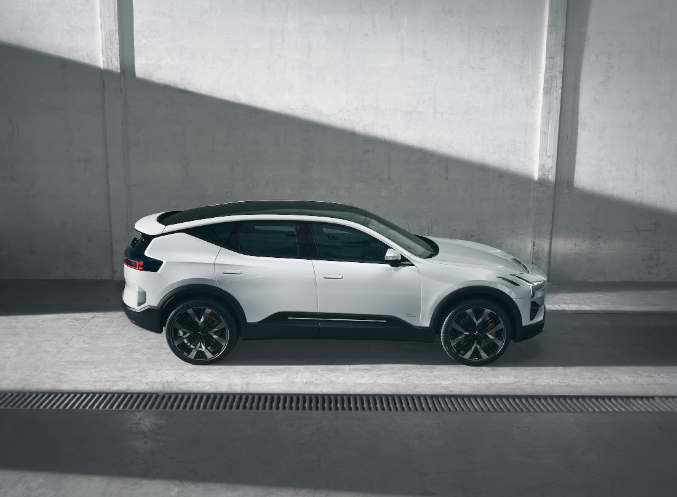
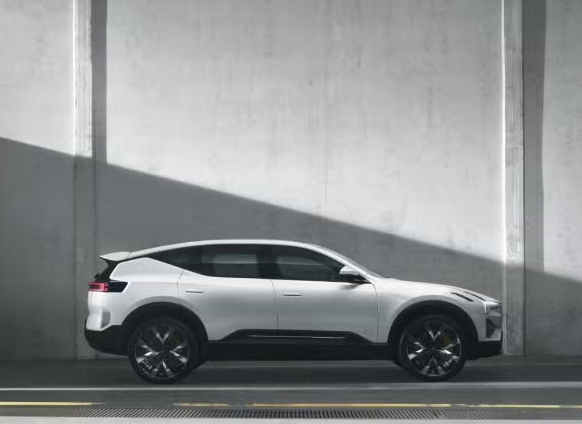
What makes the Polestar U.S. sales ban particularly jarring for automotive supply chain analysts is that the brand actually manufactures vehicles on American soil. The flagship Polestar 3 SUV is actively assembled alongside the EX90 at Volvo’s state-of-the-art plant in South Carolina. However, this localized Charleston EV manufacturing footprint was not enough to save the brand from the Commerce Department’s hammer.
Historically, foreign automakers could easily bypass trade restrictions and tariffs by setting up local assembly plants. If you build it locally and employ American workers, you avoid the heaviest electric vehicle tariffs and political pushback. But the Polestar U.S. sales ban has entirely rewritten the rulebook. It proves that final assembly location is legally irrelevant if the vehicle’s connected hardware and core software are ultimately subject to the jurisdiction of a foreign adversary. The U.S. government has made it abundantly clear: importing technology modules for local assembly will no longer shield an automaker from advanced connected vehicle restrictions.
This new reality has sent shockwaves through boardrooms from Detroit to Stuttgart, driving an unprecedented surge in demand for automotive regulatory compliance consulting. Manufacturers are currently scrambling to audit their own tiered supply chains, desperately trying to map out exactly where every single line of code and every microchip originates to avoid facing a fate similar to the Polestar U.S. sales ban.
The Financial Math: Why Surrendering Makes Strategic Sense
From the outside looking in, choosing not to appeal the Polestar U.S. sales ban might look like a total capitulation. But from a purely analytical and financial perspective, the decision is a coldly pragmatic calculation. Fighting a federal national security mandate would require years of protracted litigation, massive lobbying expenditures, and an incredibly expensive, multi-year complete redesign of the brand’s software architecture to decouple it from Geely.
Furthermore, the American market simply wasn’t pulling its weight to justify that level of investment. In the first quarter of 2026, a staggering 94 percent of Polestar’s retail sales volume came from outside the United States. America accounted for a mere 6 percent of their global deliveries.
The company has been navigating highly turbulent financial waters recently. Polestar posted a massive first-quarter net loss of $383 million in 2026—more than double its losses from the same period a year earlier—as a combination of U.S. and E.U. tariffs and vicious pricing pressure severely weighed on margins. With its gross margin falling into the negative single digits, wasting precious capital to aggressively fight the Polestar U.S. sales ban made absolutely zero business sense.
Instead, the automaker is accelerating its strategic pivot toward the luxury EV market Europe. By rapidly expanding its retail sales network across the continent and localizing manufacturing in places like the new Kosice factory in Slovakia, Polestar aims to solidify its position in a European market where regulations are more navigable and consumer adoption of premium EVs remains incredibly strong. In reality, the Polestar U.S. sales ban simply accelerated a market retreat that was likely already sketched out on the executive whiteboard.
Impacts on Current Owners, Insurance, and Financing
While the corporate entity shifts its gaze across the Atlantic, thousands of American drivers currently have a Polestar parked in their driveway. When news of the Polestar U.S. sales ban broke, immediate concerns surrounding maintenance, vehicle depreciation, and long-term software support flooded automotive forums and dealership lines.
The company’s executive spokespeople have gone on the record confirming that existing owners have nothing to worry about in the immediate future. They have guaranteed that all current warranties remain in full effect and that service networks will continue to operate under their standard terms and conditions. The brand intends to legally sell through its remaining physical inventory of the Polestar 3 and Polestar 4 before officially winding down U.S. marketing operations ahead of the 2027 model year cutoff.
However, the secondary automotive market is incredibly sensitive to brand exits. The Polestar U.S. sales ban will inevitably impact depreciation curves. As mainstream consumers hesitate to purchase a “discontinued” brand, resale values will naturally soften. This dynamic directly affects financial products tied to the vehicles. Auto lenders heavily weigh projected residual values, meaning the Polestar U.S. sales ban could lead to immediate adjustments in EV auto loan rates for used models, as banks price in the perceived risk of financing an orphaned brand.
Similarly, actuaries are likely already running the complex math on how the market exit will influence the electric vehicle insurance cost for current drivers. When an automaker pulls out of a geographic region, the long-term availability of specialized replacement parts—especially proprietary body panels, advanced sensor suites, or high-voltage battery components—becomes a severe logistical gamble. As authorized parts become scarcer, supply chains dry up, and repair times lengthen, insurers typically offset these rising operational risks by adjusting consumer premiums upward.
Conversely, for consumers looking to capitalize on the exit, the short-term outlook might present unique financial opportunities. Dealerships needing to rapidly clear out their remaining Polestar 3 and 4 inventory before the hard regulatory cutoff will likely offer highly aggressive luxury EV auto leasing deals. For the educated automotive buyer willing to assume the long-term depreciation and service risks, the Polestar U.S. sales ban might inadvertently result in some of the most financially attractive lease terms seen in the premium EV segment this decade.
Commercial Fleet Fallout
The retail consumer market is only one side of the coin; the Polestar U.S. sales ban also carries heavy implications for the B2B sector. Over the past few years, major corporations have been heavily electrifying their vehicle portfolios to meet strict ESG (Environmental, Social, and Governance) targets.
For logistics professionals handling commercial EV fleet management, absolute predictability is paramount. A commercial fleet manager needs to know that the vehicles they purchase today will have robust telematics support, easily accessible parts, and completely uncompromised software functionality for the next five to seven years. The Polestar U.S. sales ban disrupts this predictability entirely. It forces fleet operators to immediately halt any planned procurement of Geely-backed vehicles and rapidly pivot to domestic or allied-nation manufacturing alternatives.
This situation highlights the severe automotive supply chain geopolitical risks inherent in today’s highly politicized market. Fleet operators are quickly realizing that a vehicle’s software origin is just as critical to operational viability as its battery range. The Polestar U.S. sales ban serves as a massive cautionary tale: investing millions of corporate dollars in commercial fleets without heavily scrutinizing the underlying connected vehicle architecture can lead to disastrous stranded assets if federal regulations shift overnight.
What the American Market is Losing
Beyond the corporate strategy, financial metrics, and regulatory red tape, the Polestar U.S. sales ban represents a genuine cultural loss for American automotive enthusiasts. The brand brought a distinct, minimalist Scandinavian design language to an EV landscape that often feels saturated with overly aggressive styling or completely generic aerodynamic blobs.
Because of the Polestar U.S. sales ban, American buyers will miss out on the highly anticipated Polestar 6. This stunning, high-performance electric roadster, conceptualized and engineered to rival legacy sports cars like the Porsche 911 in both aesthetics and driving dynamics, will now be an exclusive sight on the coastal roads of Europe and Asia. The loss of the Polestar 6 is a poignant reminder that geopolitical trade wars don’t just shift capital—they directly dictate the caliber of engineering, art, and design that regional consumers get to experience.
Furthermore, the Polestar 4 SUV coupé, which features a highly innovative and controversial design completely lacking a rear window, will likely be the last vehicle the marque ever sells in the United States. It stands as a unique, final footnote in the brand’s brief but memorable American history.
A Blueprint for the Future of Automotive Trade
The widespread implications of the Polestar U.S. sales ban extend far beyond a single Swedish-badged EV maker. This ruling is a definitive blueprint for the next decade of international automotive trade. We are officially entering an era of intense regionalization, where the digital borders of a vehicle matter just as much as physical customs checkpoints and ocean freight routes.
The successful execution of the Polestar U.S. sales ban proves that the U.S. government is willing to aggressively leverage connected car security regulations to legally lock foreign-controlled tech out of its infrastructure. Other nations, including Canada, are already evaluating similar frameworks to prevent trade backdoors. For legacy automakers and new EV startups alike, the message from Washington is unequivocal: globalized, heavily entangled software supply chains are now a massive corporate liability. Companies will have to completely silo their data networks, physically separate their software development by global region, and prove beyond a shadow of a doubt that adversarial nations do not have backdoor access to their vehicles’ telematics.
As we look toward the 2030 hardware mandates, the aftershocks of the Polestar U.S. sales ban will force a massive, multi-billion-dollar restructuring of how cars are designed and engineered. The decoupling of automotive hardware and software across geopolitical lines is no longer a theoretical debate at industry conferences; it is an active, heavily enforced regulatory requirement.
Moving Forward in a Segmented Market
Ultimately, the Polestar U.S. sales ban represents a critical inflection point in automotive history. It is the exact moment when the digital cold war officially intersected with the American driveway. By choosing not to fight the government mandate and intentionally retreating to the luxury EV market Europe, Polestar is publicly acknowledging a difficult, undeniable truth: the era of the truly global, frictionless, borderless automobile is over.
As the regulatory dust settles on the Polestar U.S. sales ban, the broader auto industry must immediately adapt to a highly fragmented reality. Automakers must now master a complex, overlapping web of electric vehicle tariffs, localized software mandates, and stringent national security audits just to sell a car. For American consumers, it unfortunately means fewer choices on the lot, potentially higher prices as compliance costs are passed down, and the reality that some of the world’s most beautiful and innovative electric vehicles will never legally touch U.S. pavement.
If your organization is actively navigating these unprecedented shifts in the global supply chain, or if you are seeking absolute clarity on how emerging connected vehicle regulations will directly impact your commercial procurement strategies, proactive planning is essential. The regulatory landscape is evolving daily, and as we have just seen, the cost of non-compliance is total market exclusion. Connect with our automotive advisory team today to explore comprehensive, future-proof strategies that safeguard your fleet operations and ensure total regulatory compliance in this volatile new era of automotive technology.