The Polestar U.S. Sales Ban: Strategic Retreat, Regulatory Fallout, and the Future of Connected Cars
The global automotive landscape has officially crossed a regulatory Rubicon, fundamentally altering how international supply chains and foreign ownership dictate market access. After months of intense speculation, back-channel negotiations, and closed-door dialogues with the U.S. Department of Commerce, the highly publicized Polestar U.S. sales ban has transitioned from a looming threat to a permanent, market-altering reality. Starting with the 2027 model year, the Swedish-born, Chinese-backed automaker is legally barred from importing and selling its vehicles within the United States. Rather than dragging the issue into a protracted, high-stakes legal battle, Polestar’s executive leadership has officially announced it will not appeal the sweeping decision. Instead, the company is executing a formal, permanent retreat from the American market. Having spent the last ten years analyzing automotive regulatory shifts, franchise economics, and global EV supply chains, I view the Polestar U.S. sales ban as a definitive watershed moment for the industry. This is no longer merely a story about a single electric vehicle brand failing to gain traction; it is a profound restructuring of global automotive trade. The Polestar U.S. sales ban serves as the blueprint for how software origin, corporate ownership, and smart vehicle cybersecurity will unconditionally govern the future of the automotive sector.
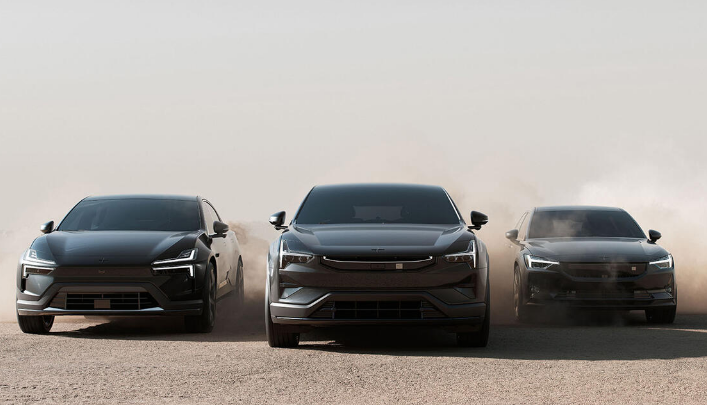
To fully comprehend the unprecedented magnitude of the Polestar U.S. sales ban, we must dissect the underlying legislative framework that triggered the exile: the Department of Commerce connected vehicle rule. Finalized by the Bureau of Industry and Security (BIS), this aggressive policy explicitly restricts the import and sale of vehicles equipped with connectivity technologies tied to foreign adversaries, primarily zeroing in on China and Russia. The justification is strictly rooted in national security. Modern electric vehicles are essentially rolling supercomputers, relying heavily on advanced Chinese connected vehicle technology, cellular modules, Wi-Fi, Bluetooth arrays, and automated driving software to function safely. Both the current and previous federal administrations have consistently argued that these integrated systems could easily be weaponized. The prevailing fear is that adversarial governments could exploit these networks for mass data harvesting—tracking the movements of citizens, military personnel, and critical infrastructure—or worse, execute the remote manipulation of thousands of vehicles simultaneously on American roads. Consequently, the Polestar U.S. sales ban represents the most aggressive enforcement of this national security doctrine to date. Despite Polestar’s historical roots in Gothenburg, Sweden, its deep financial and structural entanglement with its majority owner, the Chinese automotive conglomerate Geely Holding Group, subjected the brand to fatal regulatory scrutiny. When the BIS issued its final ruling denying authorization for the automaker’s future models, the Polestar U.S. sales ban became an unavoidable reality.
In analyzing the fallout, one of the most intellectually fascinating aspects of the Polestar U.S. sales ban is the stark contrast it presents when compared to its sister brand, Volvo. Both automakers operate under the expansive Geely corporate umbrella, yet Volvo successfully navigated the regulatory minefield to secure a highly coveted operational exemption in May 2026. This allowed Volvo to continue selling its connected vehicles in the United States, effectively avoiding the fate that sealed the Polestar U.S. sales ban. Why did the Volvo Geely exemption succeed where Polestar’s efforts failed miserably? The answer lies buried in the intricate nuances of corporate governance and software architecture isolation. Volvo proactively submitted exhaustive, granular data security details to the Office of Information and Communications Technology and Services. Furthermore, Volvo maintains an independent public trading structure and a legacy U.S. manufacturing footprint that significantly insulated it from Geely’s central engineering hub. Polestar, conversely, is deeply intertwined with Geely’s native tech platforms, heavily sharing core codebases, over-the-air update mechanisms, and connected car security solutions with its Chinese parent. For manufacturing executives currently mapping their long-term strategies, the Polestar U.S. sales ban underscores an urgent, existential need for aggressive automotive regulatory compliance consulting. Supply chain and software sourcing decisions made a half-decade ago are now yielding catastrophic market access denials. Regulators have drawn a rigid line in the sand: passive investment by a Chinese entity is a manageable risk, but direct operational control is an automatic disqualifier.
The sheer scale of the disruption caused by the Polestar U.S. sales ban extends far beyond corporate boardrooms; it is currently wreaking severe financial havoc across the brand’s American retail network. Polestar operates 32 franchised “Spaces” across the United States, and these independent dealer operators have been thrust into an unprecedented existential crisis. The sudden, unceremonious nature of the Polestar U.S. sales ban has left these retailers saddled with rapidly depreciating current models, canceled future inventory pipelines, and millions of dollars in aggressively mandated facility upgrades that will never see a return on investment. Unsurprisingly, the legal machinery is already mobilizing. We are witnessing the groundwork for what could become the largest EV franchise lawsuit of the decade, as operators allege that the brand’s rapid U.S. exit is a calculated financial retreat conveniently masked as a regulatory inevitability. For dealership principals caught in the crossfire, retaining an elite auto franchise attorney has never been more critical. State-level automotive franchise laws are notoriously robust, heavily favoring the retailer. In most jurisdictions, when an automaker abandons a market without declaring outright bankruptcy, they are statutorily required to make their franchisees financially whole. While Polestar executives have stated they are attempting to “manage this transition” rather than immediately terminating contracts, the ultimate financial exposure is staggering. The automaker could be strictly liable for comprehensive dealer buyback compensation, a crippling expenditure that includes repurchasing all unsold vehicle inventory, reimbursing the cost of specialized EV diagnostic equipment, and potentially paying out the fair market value of the franchise rights themselves.
Furthermore, the operational liabilities triggered by the Polestar U.S. sales ban bleed heavily into the commercial sector. Companies specializing in electric vehicle fleet management that previously integrated Polestar models into their corporate fleets are now facing severe logistical nightmares. Without guaranteed, federally authorized over-the-air software updates, these vehicles present massive cybersecurity vulnerabilities. The insurance sector is already reacting, recalculating the commercial auto liability risks associated with operating technologically unsupported, internet-connected vehicles on public highways. A fleet of unsupported EVs isn’t just a maintenance headache; it is a moving liability that could suffer catastrophic software bricking or remote breaches, driving up insurance premiums for early adopters who mistakenly trusted the brand’s longevity in the American market.
With the Polestar U.S. sales ban violently slamming the door on North American growth, the automaker’s leadership is executing a rapid, defensive strategic realignment. Polestar has officially confirmed it will channel its remaining capital strictly into regions where it commands a strong brand presence and faces fewer geopolitical headwinds. Consequently, an aggressive Polestar European market expansion is no longer merely a strategic growth pillar—it is an absolute matter of corporate survival. CEO Michael Lohscheller recently highlighted that the U.S. market accounted for a surprisingly low 6% of the brand’s global retail volume in recent quarters, whereas Europe represents nearly 80% of its critical sales throughput. By actively localizing the manufacturing of upcoming models—such as shifting production of the Polestar 7 to Volvo’s new facilities in Slovakia—the brand hopes to permanently insulate itself from the transatlantic trade wars that culminated in the Polestar U.S. sales ban. However, phrasing this exit as a simple “focus on Europe” glosses over a deeply painful reality. Just last year, the company was forced to entirely discontinue U.S. sales of the Polestar 2 sedan after being hammered by a crippling 100 percent tariff on Chinese-built electric vehicles. The brutal combination of those punitive tariffs and the final, sweeping authority of the Polestar U.S. sales ban simply proved too heavy a burden for the automaker’s balance sheet to absorb.
It would be a grave analytical error to view the Polestar U.S. sales ban as an isolated, standalone incident. The Department of Commerce has forcefully signaled that this targeted action is merely the opening salvo in a much broader, uncompromising campaign to secure American digital infrastructure. Other legacy and niche automotive brands with deep, structural ties to Chinese engineering are currently sweating under the regulatory microscope. Lotus, another high-performance subsidiary of Geely, faces identical software scrutiny and could easily be the next casualty. Even Western juggernauts are not entirely immune; Mercedes-Benz, which counts Geely’s founder Li Shufu as a nearly 10% shareholder, must constantly prove its software independence to maintain U.S. market access. The precedent firmly established by the Polestar U.S. sales ban dictates an entirely new reality for global manufacturing: software origin and cloud architecture now completely supersede physical vehicle assembly locations. A vehicle could be physically stamped, welded, and assembled in South Carolina, but if its primary diagnostic software pings a server in Shenzhen or relies on a backend developed by a Chinese state-linked entity, it will face the exact same regulatory execution as Polestar. This relentless scrutiny forces original equipment manufacturers (OEMs) to entirely map and sanitize their digital supply chains.
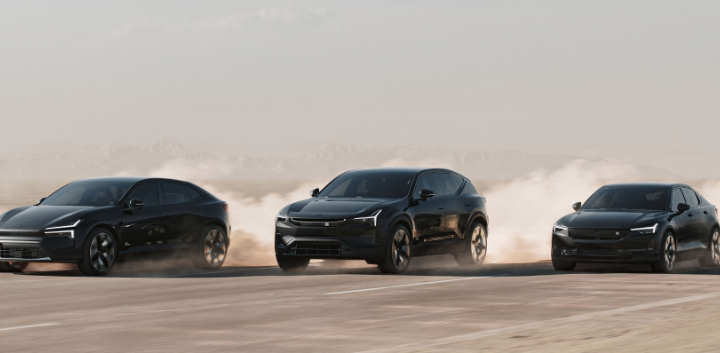
For the average American consumer who already parked one of these vehicles in their driveway, the Polestar U.S. sales ban has triggered a wave of justifiable panic. While the manufacturer has offered hollow reassurances that it will continue to support existing customers and legally sell through its remaining pre-2027 authorized inventory, the long-term viability of these highly digitized cars is deeply compromised. Modern EVs require constant software patches to manage battery thermals, update infotainment features, and patch critical security exploits. If the federal government views the brand’s software pipelines as an active national security threat, the longevity of dedicated U.S. service centers and continuous cloud support remains highly questionable. Consequently, we are witnessing a complete collapse in residual values. The Polestar U.S. sales ban has caused secondary market prices for used Polestar models to plummet overnight, leaving early adopters heavily underwater on their auto loans. The Polestar U.S. sales ban serves as a harsh, permanent warning to consumers investing in new-age, tech-heavy vehicles: a smart car is only as reliable and functional as the company legally permitted to maintain its underlying code.
Ultimately, the cascading ramifications of the Polestar U.S. sales ban will reverberate through the global automotive sector for decades. It marks the definitive, undeniable end of the frictionless globalization era for the auto industry. The previous business model—where an automaker could seamlessly blend cheap Chinese software architecture with Western brand heritage to maximize profit margins—is dead. It is being rapidly replaced by a fractured, hyper-regionalized market heavily policed by uncompromising national security mandates. Automakers can no longer afford the luxury of designing a single, globally compliant connected vehicle platform if they intend to do business in the United States. The Polestar U.S. sales ban has definitively proven that the geopolitical origin of an automaker’s code is now vastly more important than the horsepower of its engines or the capacity of its batteries.
If you are a dealership principal facing stranded inventory, an automotive executive navigating fractured digital supply chains, or a fleet manager heavily invested in connected EVs, the regulatory landscape is shifting faster than at any point in automotive history. You cannot afford to wait for the next federal ruling to decimate your market access or strand your commercial assets. Contact our specialized regulatory and compliance advisory team today to aggressively audit your connected tech supply chains, safeguard your franchise rights, and permanently secure your operational future against the rising tide of global trade restrictions.