One industry expert spent ten years advising property clients, and the same dividing line kept showing up.
Some buyers struggled and others prospered, yet the gap between them rarely came down to a single well-timed purchase. It came down to whether each buyer worked from a sound long-term strategy. He says that holds for first-time homebuyers, for veteran investors adding to a portfolio, and for people planning their retirement. In his view, a clear blueprint makes the market’s complexities far more manageable. For current economic conditions, he proposes a framework built on six parts: goals, finances, market knowledge, diversification, operations, and an exit.
The first part is goals. An investor should settle on a definition of success before looking at one listing or applying for any financing. Some people want steady passive income from rental yields. Others want to build substantial equity, or to buy a commercial property they eventually plan to occupy themselves. Whichever target is picked, it shapes the entire roadmap. Three questions help sharpen it. What is the core investment timeline? Which asset classes and property types suit the investor’s risk tolerance? And how much day-to-day involvement is wanted?
After that, the goal gets divided into smaller pieces, with short-term and long-term objectives kept apart. Flipping properties produces Immediate liquidity, while long-term appreciation and rental income build wealth through compounding. Concrete income milestones follow. A target of $2,500 per month in net rental cash flow within five years, for example, keeps decision-making disciplined. Every acquisition also needs its own defined role. A property might be a purely commercial investment, or it might double as a personal lifestyle asset, such as a vacation retreat.
The second part is a full audit of personal finances, a step no investor can skip. It begins with the current balance sheet: liquid savings, monthly income, and existing debt. That snapshot shows how much buying power is available and which commercial real estate loans or conventional mortgages fit the situation.
The audit has three components. The first is a comprehensive budget that maps every projected cash inflow and outflow. It has to include the hidden costs of acquiring a property, namely down payments, closing fees, and inspections, along with reserves large enough to absorb any cash-flow shortfall. The second is a stronger credit profile. Lenders give borrowers with high credit scores better mortgage refinancing rates and lower interest expenses, so a score well above 740 is the benchmark for qualifying for the best loan terms. The third is professional help. A certified financial planner can confirm that property purchases line up with the investor’s broader wealth management and retirement goals.
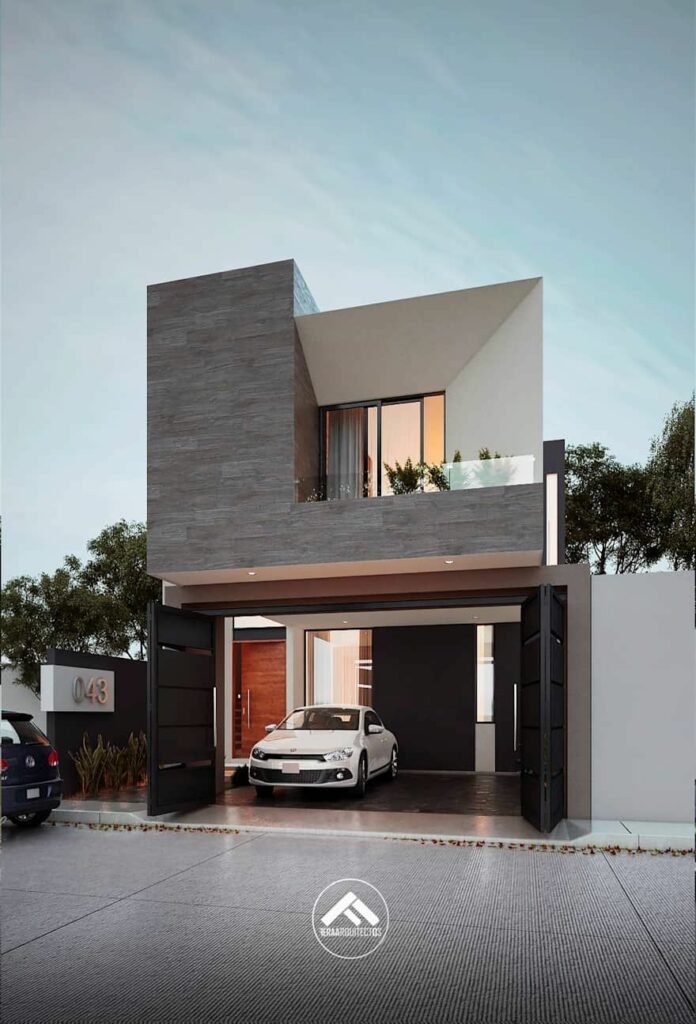
Money, though, covers only half the ground. The other half is the market itself, and in property investment, deep local expertise offers the best protection against volatility. Investors should study current economic conditions, property valuation trends, and demographic shifts in the metropolitan areas they are targeting.
Three considerations deserve special attention. The first is location and neighborhood growth. Expanding job markets, top-tier school districts, and major infrastructure upgrades all point toward future appreciation. The second is supply and demand. Local inventory levels are worth tracking, because markets with constrained housing supply and surging buyer or tenant demand tend to show natural price stability and growth. The third is the macroeconomic picture. Interest rate movements, inflation metrics, and employment growth forecasts directly influence both real estate values and borrowing costs.
This research is never a one-time chore. The property market is dynamic, and it shifts with tax policy changes, economic cycles, and housing legislation. Continuing education keeps an investor competitive and agile, ready to adjust tactics whenever conditions change.
The third part, diversification, rests on a simple point: concentrated risk makes a portfolio fragile. To reduce systemic risk, holdings should be spread across different geographic regions, tenant demographics, and asset classes, with residential rentals held alongside commercial real estate. Single-family homes and multi-family apartments deliver dependable cash flow and steady long-term appreciation. Office buildings, retail centers, and industrial warehouses, by contrast, often carry higher capitalization rates and longer lease structures.
Diversification takes three forms. Geographically, investing across multiple states or cities means a downturn in one local economy does not pull down the whole portfolio. By asset class, balancing single-family houses against multi-family units and commercial spaces stabilizes overall returns. By strategy, pairing steady buy-and-hold income properties with selective fix-and-flip projects optimizes cash flow and capital velocity.
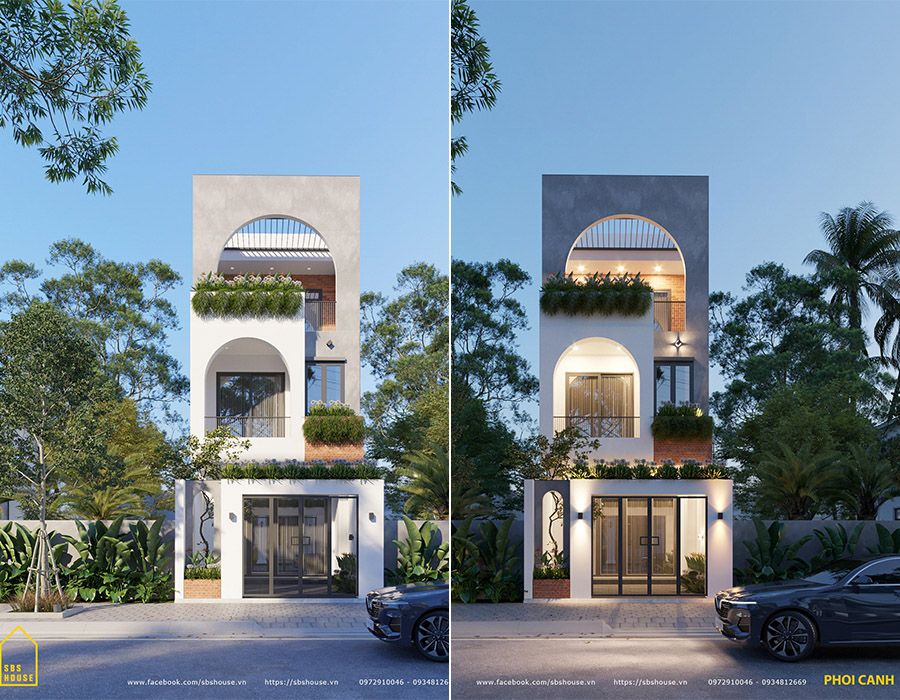
The fourth part is operations, because property management and maintenance determine net operating income. An investor should decide early whether to run the units personally or to hire a property management company for daily oversight. Self-management gives full control and saves on management fees, but it consumes a significant amount of personal time on tenant screening, lease enforcement, and maintenance coordination. Third-party management firms take over leasing, maintenance, and rent collection in exchange for a percentage of the monthly rent. That arrangement suits investors scaling up across multiple doors, as well as anyone who prefers a passive, hands-off approach.
Sound maintenance planning rests on three habits. Routine property inspections twice a year catch small problems before they turn into costly structural repairs. Each year, 1% to 2% of the property’s total value should go into a dedicated repair fund for capital expenditures. And building relationships with licensed plumbers, electricians, and general contractors can earn priority service and competitive labor rates.
The final part is the exit. A plan for entering the market is incomplete without a plan for leaving it. Knowing how and when to liquidate, transition, or pass on assets protects the profits an investor worked hard to earn. Three exit paths stand out. The first is strategic property liquidation: selling during peak market cycles to capture maximum capital gains, then redeploying the proceeds into higher-yielding assets. The second is mortgage refinancing, which taps built-up equity through a cash-out refinance to fund the next acquisition while the core income-producing assets stay in place. The third is estate planning, which means setting up family trusts or using legacy planning to transfer properties to heirs while minimizing estate taxes and probate complications.
Taken together, these six elements form a single discipline. Lasting wealth in real estate is a marathon that rewards patience, rigorous analysis, and disciplined execution. Clear goals, optimized financing, a firm grasp of market fundamentals, and careful upkeep are what produce a resilient portfolio. The remaining question is whether you are ready to take the next step toward financial independence, and whether a personalized strategy session could help you chart your own path to real estate success.
In the end, the expert’s decade of experience points to one conclusion: it is the plan, not any single deal, that builds lasting wealth in property. Goals, finances, market knowledge, diversification, operations, and an exit each carry part of the load.
If this breakdown gave you something useful, hit the subscribe button so the next video lands in your feed right away. Give it a like if it earned it, and switch on the notification bell so the latest news reaches you the moment it goes live.