By 2028, Melbourne will need 21,600 more dwellings than it has.
Builders are on course to finish just 8,900 apartments in the same period, leaving a 60 percent gap between what the city requires and what it will get. That gap anchors an investment argument now being made about the city’s central district.
An analyst with a decade in the Australian property market calls the CBD of the Victorian capital the strongest in the country. Whenever clients ask where to place capital for durable, long-term returns, the answer stays the same: the Melbourne core. The analyst’s position draws on years of studying market cycles, economic shifts, and urban planning documents, including the Melbourne CBD Market Outlook 2025 report, which Far East Consortium commissioned from Urbis. For investors who want strong rental yields and meaningful capital growth from a single holding, the analyst describes Melbourne CBD apartments as a strategically well-placed asset.
The first pillar is people, since property follows population. Melbourne is projected to pass Sydney as Australia’s largest urban center by 2032, and forecasts place its population at 7.45 million by 2040. Sustained, heavy Immigration fuels that growth. In 2024 alone, 446,000 new overseas arrivals settled in the city, and each one created Immediate demand for housing. When demand outpaces supply by this much, capital values and rental returns tend to face upward pressure. A structural shortage of this kind favors Melbourne CBD property investment and can help insulate investor capital from broader economic swings.
The second pillar is land, which is finite. The physical limits of the central grid make greenfield projects and major infill developments extremely rare. As available sites disappear, existing high-density housing stock is positioned to appreciate faster.
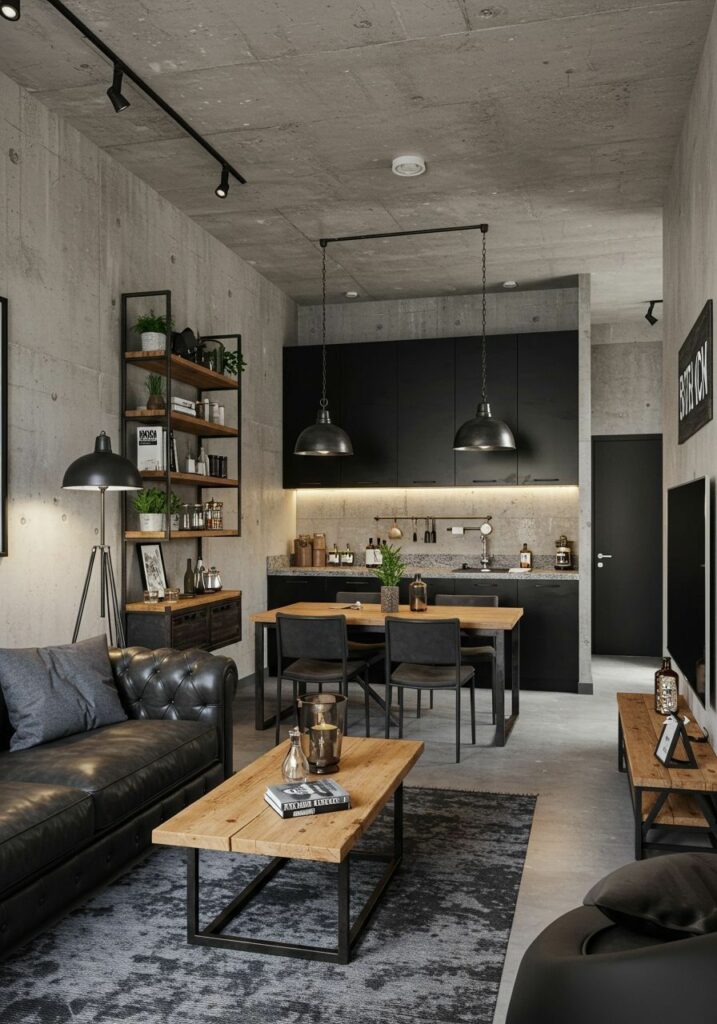
The third pillar is the cost of entry. For decades, the Australian dream meant a quarter-acre suburban block, but changing socioeconomic conditions and lifestyle preferences have rewritten the investment math. In 2024, the median price of a Melbourne CBD apartment sat roughly 56 percent below the median for a detached suburban house. A lower purchase price lets investors secure prime inner-city property with far less capital at risk, which leaves more room to diversify.
Rental figures from the center point the same direction. Median weekly rents climbed to $750, up 9 percent from earlier cycles, while vacancy averaged only 2.4 percent. Newly built apartments are consistently producing gross rental yields of about 4.8 percent, which yields cash flow that is both Immediate and dependable.
Public spending adds another layer. Infrastructure investment drives long-term property values, and Victoria’s multibillion-dollar pipeline is reshaping connectivity, liveability, and asset values across the metropolitan area. The projects form part of a broader commitment of $107 billion, and five of them stand out.
The Melbourne Greenline is a $224 million initiative that turns the north bank of the Yarra River into a 4-kilometer linear park, boosting the recreational and lifestyle appeal for CBD residents. The Suburban Rail Loop, a major rail project due for completion around 2035, is designed to link outer transit hubs and simplify regional commuting. The Queen Victoria Market Renewal is a $268 million revitalization that brings new public spaces, dining precincts, and community activations to one of the city’s most cherished historical landmarks. The West Gate Tunnel Project opens an alternative arterial corridor, easing congestion and Improving commercial travel between the western employment hubs and the city center. The North East Link, the largest road project now underway in Victoria, connects major ring roads and shortens cross-city travel times. For anyone investing in Melbourne CBD apartments, being close to these civic upgrades helps residential assets hold both their appeal and their long-term liquidity.
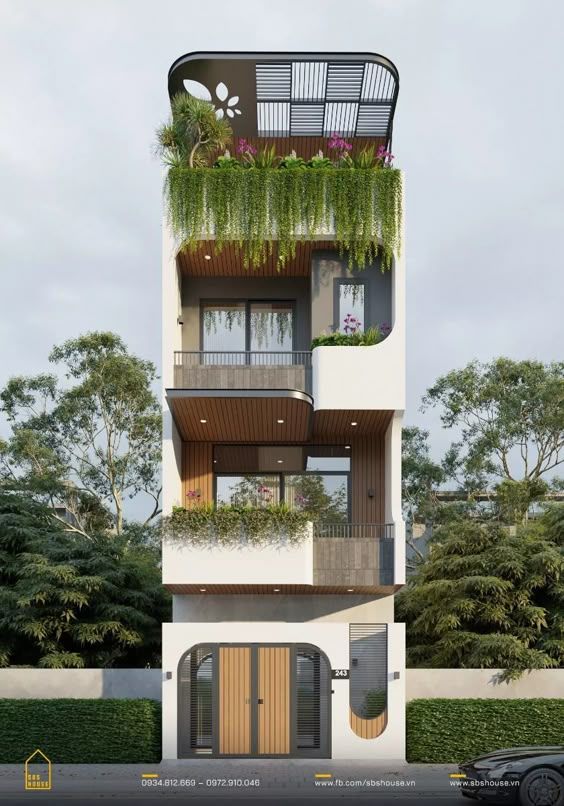
The wider economy matters too, and Australia’s macroeconomic fundamentals look very stable. Unemployment stands at 4.0 percent, comfortably below its ten-year historical average of 5.3 percent. Consumer sentiment has rebounded sharply, with the ANZ-Roy Morgan Index climbing significantly as national inflation eased to about 2.8 percent.
Financing conditions are trending the same way. Major institutions such as ANZ and NAB are expected to adjust interest rates, and the cash rate set by the Reserve Bank of Australia is expected to settle between 3.35 percent and 3.85 percent. Borrowing costs are therefore shifting in favor of leveraged investors. Lower financing hurdles combined with cooling inflation make a textbook window of opportunity, one that opens before competition from the wider pool of retail buyers reaches its peak.
Execution counts as much as timing. Navigating Melbourne CBD property investment demands a clear-headed, analytical approach, and success does not come from speculative buying. It comes from targeting assets with superior build quality, efficient floor plans, proximity to upcoming infrastructure nodes, and proven tenant appeal. With a severe housing deficit, strong population momentum, and an enviable lifestyle offering, the inner-city apartment market stands out as a premier vehicle for wealth creation.
Put together, the numbers describe a city adding residents far faster than it adds homes, supported by heavy public investment and steady economic indicators. As 2028 draws closer, one question hangs over the market: how will a pipeline of 8,900 apartments answer a need for 21,600 dwellings?
If this report gave you something useful, tap subscribe so the next one lands right in your feed. A like helps the video reach more viewers, and switching on the notification bell means the latest news never slips past you.”