Ask a real estate professional with ten years in the business whether to buy or rent, and the reply barely shifts from client to client.
This one has walked hundreds of buyers through their purchases and lived through several economic cycles, and the verdict stays put. Renting gives breathing room to anyone who might need to move on short notice. Owning property, though, is the base on which lasting wealth gets built. Veteran investors, the argument runs, never judge a housing choice by the cash that exits their account every month. They look at where their net worth is heading. Buyers in fast-growing suburban hubs, among them the busy residential corridors of Tripunithura, have landed in the same place: buying wins over leasing by a wide margin.
The reasoning starts with where each payment ends up. A rent check goes to the landlord. A mortgage installment goes toward equity that remains with the buyer. That contrast between money spent and money invested sits beneath almost every case for owning a home, and it explains why so many tenants ultimately make the jump.
Run the numbers and the picture sharpens. Rent is a pure expense, with the entire 100% leaving your hands for good. A mortgage operates like a forced savings plan, because every installment trims the principal while building equity at the same moment. Across 10 to 15 years, that steady grind turns a tenant into an owner and rewrites the household balance sheet.
Rising prices widen the divide. Everyday goods and rental rates both climb year after year, and real estate has long served as a solid shield against that drift. Nearly everything else grows more costly, yet appreciation pushes up the worth of the property in your name. Wealth compounds, and your financial footing gets sturdier.
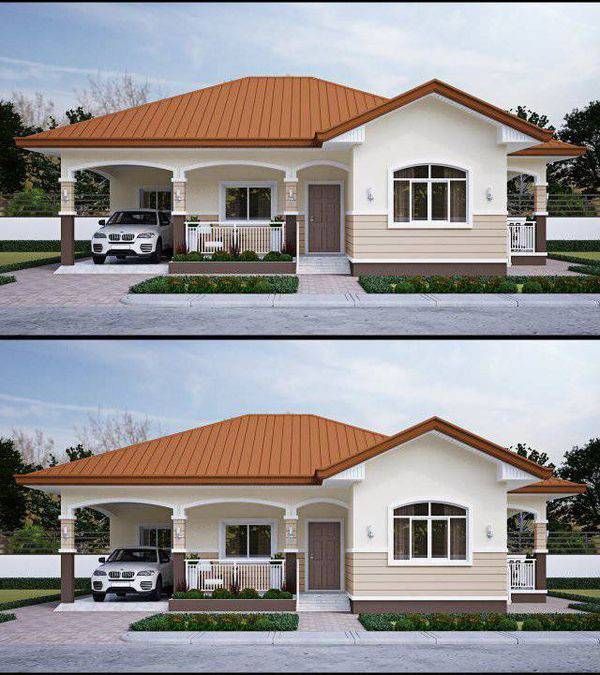
Renters absorb those pressures first. Landlords commonly lift the price of a lease at renewal, which forces a tenant to swallow a sharp increase or take on the draining, pricey chore of moving. A home loan on an apartment locks the monthly outlay in place. Choose a fixed-rate mortgage and your housing expenses become completely predictable. Neighbors who rent may face yearly rent hikes of 5 to 10%, while your baseline housing cost holds steady. After the loan is fully amortized, you live rent-free for life, which releases a large amount of cash flow for retirement or other investments.
A purchased apartment can also bring in money. Real estate is unusually versatile because it can double as an income-generating asset. With a spacious 2 BHK or 3 BHK unit, you keep the choice of building passive income from the space. In high-demand residential pockets like Tripunithura, rental yields remain exceptionally strong. A spare room could be leased out, or the whole property could be rented while your career takes you elsewhere. Both paths give the owner a secondary revenue stream that can comfortably cover upkeep or feed an investment portfolio.
The tax code piles on more advantages. Government incentives attached to buying property are ones that renting can never match. Tax rules lean heavily toward homeowners through strategic deductions on home loan interest and principal repayments. Those deductions shave a meaningful amount off annual taxable income, functioning as a quiet subsidy on the purchase. First-time homebuyers can gain even more, since assorted government schemes and structural incentives make entering the property market especially rewarding.
Borrowing power down the road is another place ownership pays off. A mortgage demands financial discipline, and that habit seeps into every other corner of your money life. Regular, on-time EMI payments show up as positive data points with credit bureaus and build a robust credit history quickly. A high credit score then widens your borrowing capacity, whether the goal is financing a business venture, purchasing a second property, or locking in favorable rates on other loans. Homeownership instills habits that keep paying dividends for decades.
Control over your surroundings draws another line between the two paths. Landlords rarely welcome tenants who want to tear down walls, lay custom hardwood, or gut the kitchen. A renter lives inside boundaries that someone else has drawn. An owner meets no such limits. You can paint the living room in moody earth tones, add luxury smart-home automation fixtures, or redesign the whole kitchen layout, on your own schedule and with no landlord’s approval. Investing in a premium apartment lets you shape a home around your own taste, which Improves your daily quality of life.
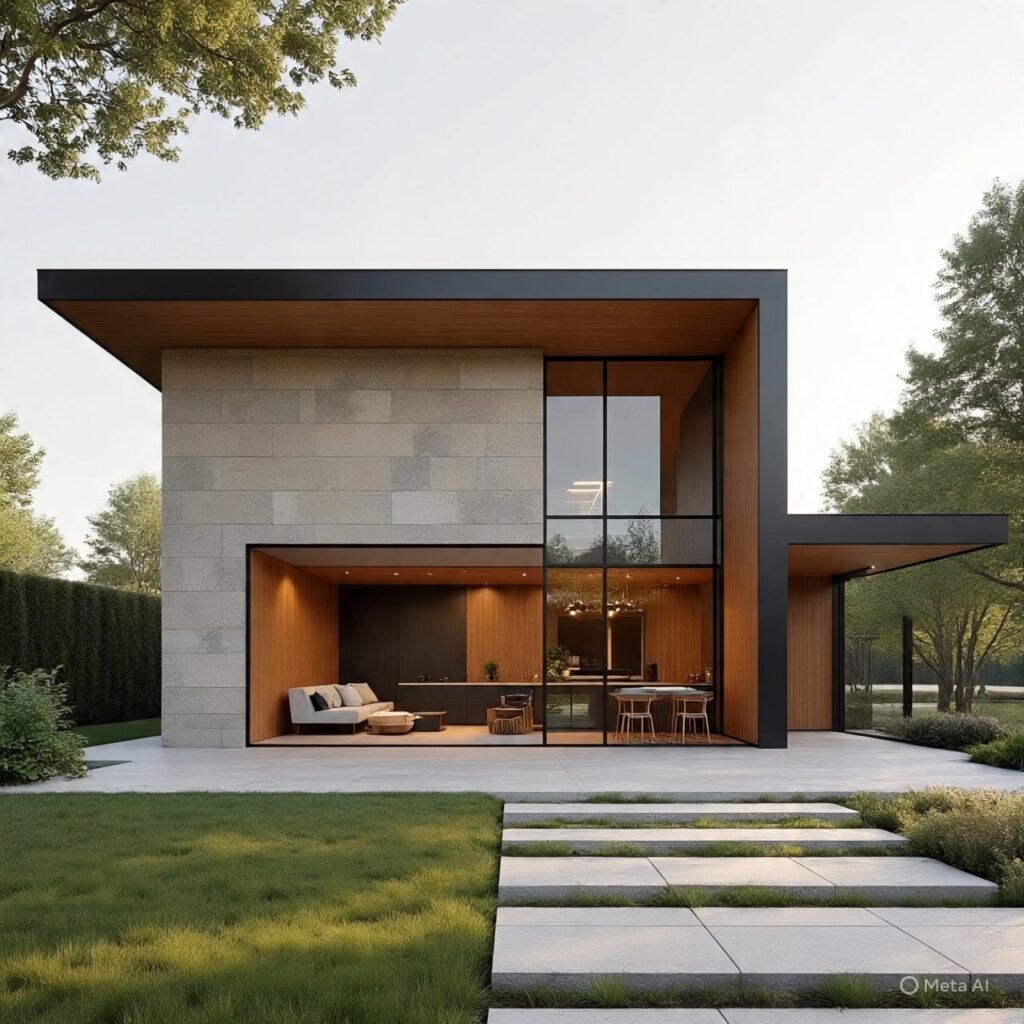
Some benefits never appear on a spreadsheet. Bouncing from one rental to the next wears people down emotionally, and families with children feel it most, because kids need stable school districts and friendly neighborhood communities. A unit in a modern gated community or luxury apartment complex opens the door to superior shared amenities: landscaped parks, state-of-the-art fitness centers, swimming pools, and round-the-clock, multi-tier security. A professionally managed complex from a top builder delivers pristine infrastructure, proper maintenance, and a tranquil setting that standalone rental houses rarely match.
Four questions surface again and again in this debate, and the answers follow from the points above. Why is buying better than renting? Buying builds long-term equity, shields you from erratic rent increases, and hands you complete creative freedom over where you live, while renting returns nothing financially. What is the biggest advantage of buying an apartment instead of renting one? Equity accumulation. Each monthly payment feeds a tangible asset that appreciates over time, rather than reducing someone else’s mortgage. How do apartments compare with independent houses in lifestyle terms? Apartments bring integrated community living, top-tier security, shared recreational amenities, and much lighter individual maintenance duties. Does real estate hedge against inflation? It does. Property values and rental equivalents rise naturally alongside inflation, so your purchasing power stays protected and the asset stays ahead of traditional cash savings.
For anyone exploring apartments for sale in Tripunithura, a growth-oriented market is a smart step toward enduring financial freedom. At Siddhi Homes, the company takes pride in crafting premium living spaces engineered for comfort, absolute security, and robust future appreciation. Its latest residential projects are open to explore today, offering a first confident step toward owning a home that truly belongs to you.
Moving from tenant to owner is a turning point for a household’s finances, combining wealth building, steady housing costs, a stable daily life, and long-term security in a way renting cannot. Fixed payments, tax deductions, a stronger credit profile, and creative control all trace back to one distinction: whether the monthly payment disappears into a landlord’s account or grows as an asset under your own name.
If this breakdown helped you weigh your options, tap subscribe so the next one reaches you right away. Give the video a like if it earned one, and turn on the notification bell so the latest news arrives the moment it drops.”