Every year the envelope shows up, and every year renters tense up before they open it.
Inside sits the renewal notice, and it nearly always carries a bigger number than the one before.
That recurring jolt is a direct result of rental inflation, which stems from market demand and cost-of-living adjustments. Anyone who has leased for a couple of years or longer has felt it. A fixed-rate home loan answers with predictability: the principal and interest portions of the monthly payment are locked at one amount. Housing costs across the rental market keep climbing, but the owner sends the same sum year after year. Once the loan term ends, the household enters a rent-free phase, and in retirement its income carries no housing overhead at all.
I have advised residential buyers for more than ten years, and across that span I have met hundreds of families at one particular crossroads: continue renting or become owners. The decision carries weight because it ties hard arithmetic to a personal craving for stability. Through complete market cycles, inflation surges, and neighborhoods whose character shifted, the figures and the psychology have both led me to a single conclusion. Purchasing a home, especially in a high-demand urban corridor, redirects the long-term path of a family’s wealth.
Today’s market talk usually opens with monthly cash flow, and experienced investors and financial advisors see where that falls short. Lining up a rent payment against a mortgage payment, then stopping, fixes attention on a handful of trees and misses the woods. A sharper question asks what each option provides in security, wealth building, and peace of mind. By all three yardsticks, buying an apartment delivers something that leasing does not.
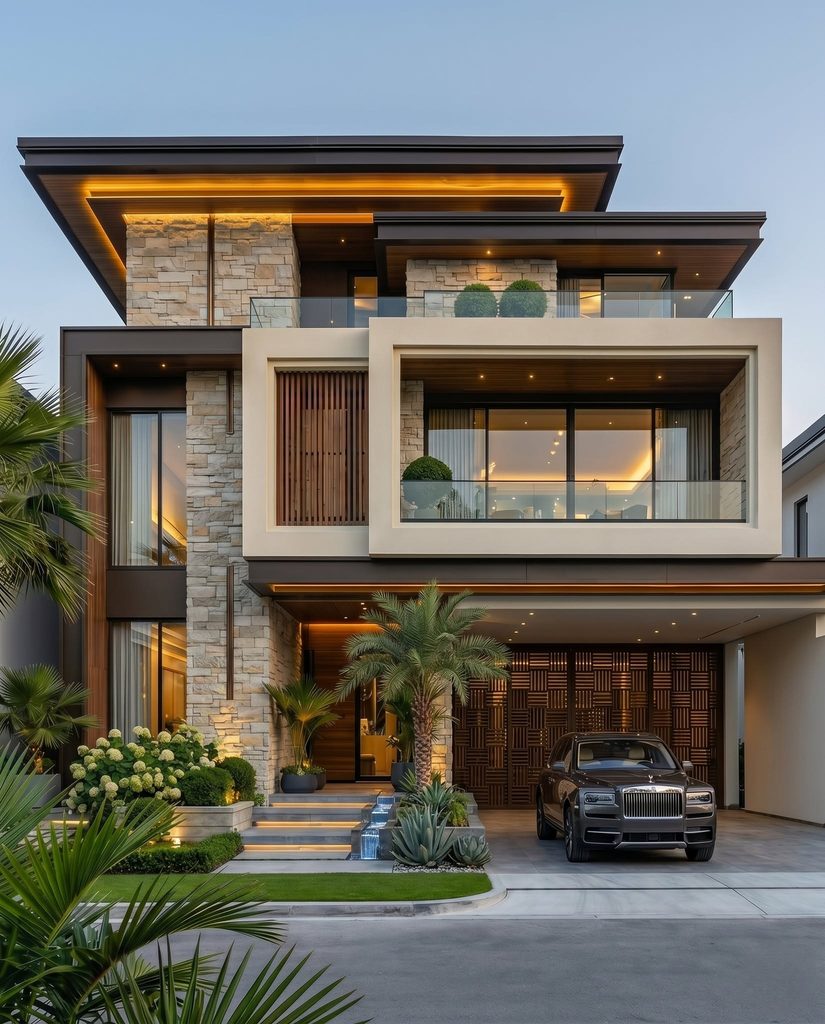
Consider first where the money ends up. Rent is gone the moment it is paid. Every dollar given to a landlord disappears without producing any return on investment. A mortgage reshapes the same monthly outlay into a compulsory savings program. A slice of every installment reduces the principal, and that slice steadily grows home equity. Imagine a money jar that also hands out dividends, and you have the apartment. Over a typical 15 to 30 years, real estate has historically risen faster than inflation, so the asset gains value without any extra effort from the owner. At the end of a lease, the tenant holds nothing after years of payments. The owner holds a solid financial buffer, one capable of paying for retirement, education, or later investments. Compulsory saving plus appreciation is the chief financial edge of ownership. Because each payment lifts ownership equity, you are constructing your own net worth rather than underwriting a landlord’s investment holdings.
Inflation deepens the divide. Often called the silent wealth-killer of the modern era, it keeps chipping away at the purchasing power of cash left in conventional savings accounts. Real estate ranks as a premier hedge against that macroeconomic pressure. As construction materials, labor, and land grow more expensive, existing properties tend to gain value in step. Renters live through the flip side of this same force, since landlords raise rates to match inflation. Owners instead see their asset appreciate, and the market gains they capture shield their purchasing power.
Government policy leans toward owners as well. Public authorities worldwide understand how much stable housing means for society, and they express that through sizable tax advantages for buyers, benefits renters never receive. Homeowners can deduct both home loan interest and principal repayments, which trims total taxable income. Regional and national incentives for first-time buyers also make a first purchase far more reachable. These financial cushions cover a good portion of the up-front acquisition costs, and the balance sheet swings strongly toward buying.
Beyond shelter, an apartment can function as a financial instrument. A roomy multi-bedroom unit lets its owner earn passive income, either by renting a spare bedroom to a professional or by leasing out the whole property when a career move relocates the owner to a different city. In both cases the real estate produces dependable cash flow. Rental demand holds firm in thriving, high-demand residential districts, where urban expansion keeps pulling in new residents. That built-in resilience means the property can go on earning monthly revenue for its owner long after closing day.
Personal money habits benefit too. A home loan, once taken and serviced, becomes an excellent anchor for financial discipline. Knowing that each monthly commitment directly builds your net worth sharpens budgeting and encourages fiscal responsibility. A steady record of on-time mortgage payments additionally acts as a turbocharger for your credit score. Strong credit unlocks favorable borrowing terms down the line, whether the aim is to expand a real estate portfolio, fund a business, or secure low-interest loans.
Ownership also changes the feel of the place itself. A rental means living inside someone else’s space, because that is precisely what it is. Landlords routinely insert restrictive clauses into leases that bar everything from painting walls a vibrant color to securely mounting a television or upgrading kitchen fixtures. The owner enjoys absolute creative freedom. Taking out a non-structural wall to open up the kitchen is the owner’s decision alone, and so are custom hardwood flooring, smart home automation, and luxury bathroom tiling. Past the cosmetic side, ownership fosters a genuine sense of belonging. Putting down roots in a permanent community makes deep, lasting bonds with neighbors possible, rather than boxing up belongings every couple of years at a landlord’s whim.
The surroundings count as much as the interior. Standalone rental houses frequently leave residents exposed to security concerns and heavy, ongoing maintenance duties. Modern apartment complexes, especially those from reputable developers, flip that situation. Gated communities with round-the-clock surveillance, professional property management, and controlled access points add a layer of safety for families. Residents also enjoy easy access to lifestyle amenities that would cost a fortune to maintain alone: fully equipped fitness centers, landscaped parks, swimming pools, and community clubhouses. Shared facilities like these raise daily quality of life considerably while keeping personal upkeep expenses surprisingly low. Security systems, fitness centers, and green spaces come as part of the package, and professional managers handle the upkeep so residents are spared most maintenance headaches.
Gathered into one picture, the case is plain. Ownership builds equity over the long term, insulates a household from rising rents, allows complete creative freedom, and supplies a tangible asset that appreciates in value. Renting, by contrast, means recurring expenses with zero financial return. Becoming a homeowner trades a lifetime of payments toward someone else’s mortgage for a secure, appreciating asset that is yours.
If this breakdown helped you weigh renting against owning, tap subscribe and hit the like button on the video. Switch on the notification bell too, so the latest news and analysis reaches you the moment it goes up.”