Few financial questions carry as much weight for ordinary households as this one: keep paying a landlord every month, or buy a home of your own.
A real estate professional with more than a decade in the industry, who has advised hundreds of prospective buyers on exactly this choice, says the numbers keep pointing the same way across market cycles. For people who want lasting financial stability and genuine peace of mind, he argues, purchasing an apartment is the stronger option by a wide margin.
His reasoning starts with money. Property is a long-term investment that steadily builds equity. A renter’s monthly payment goes into the landlord’s pocket as a running expense and returns nothing. Ownership works more like a compulsory savings plan. Each mortgage or EMI installment raises the buyer’s ownership stake and, with it, personal net worth. Property values have also historically climbed over the years, and real estate serves as a strong hedge against inflation. The buyer’s original investment compounds, while a renter’s housing money simply drains away, leaving nothing to show once the lease ends.
Rising rent is the next factor. Rents tend to creep upward every time a lease is renewed, which erodes affordability over the long run and complicates retirement planning. A fixed-rate home loan changes that picture. Payments are structured and stable, so a buyer is shielded from rent increases set at a landlord’s discretion. While landlords raise rents to keep pace with inflation, a fixed housing payment stays anchored. Once the mortgage term ends, the owner lives rent-free for decades, which sharply lowers the cost of living in retirement.
Taxes add another layer. Governments around the world encourage homeownership through incentives that renters never see. Tax laws often allow sizable deductions on home loan interest, which reduces the annual tax bill. Parts of the principal repayment can also qualify for deductions, trimming taxable income further. Regional and national schemes aimed at first-time buyers have made entering the property market more accessible than before.
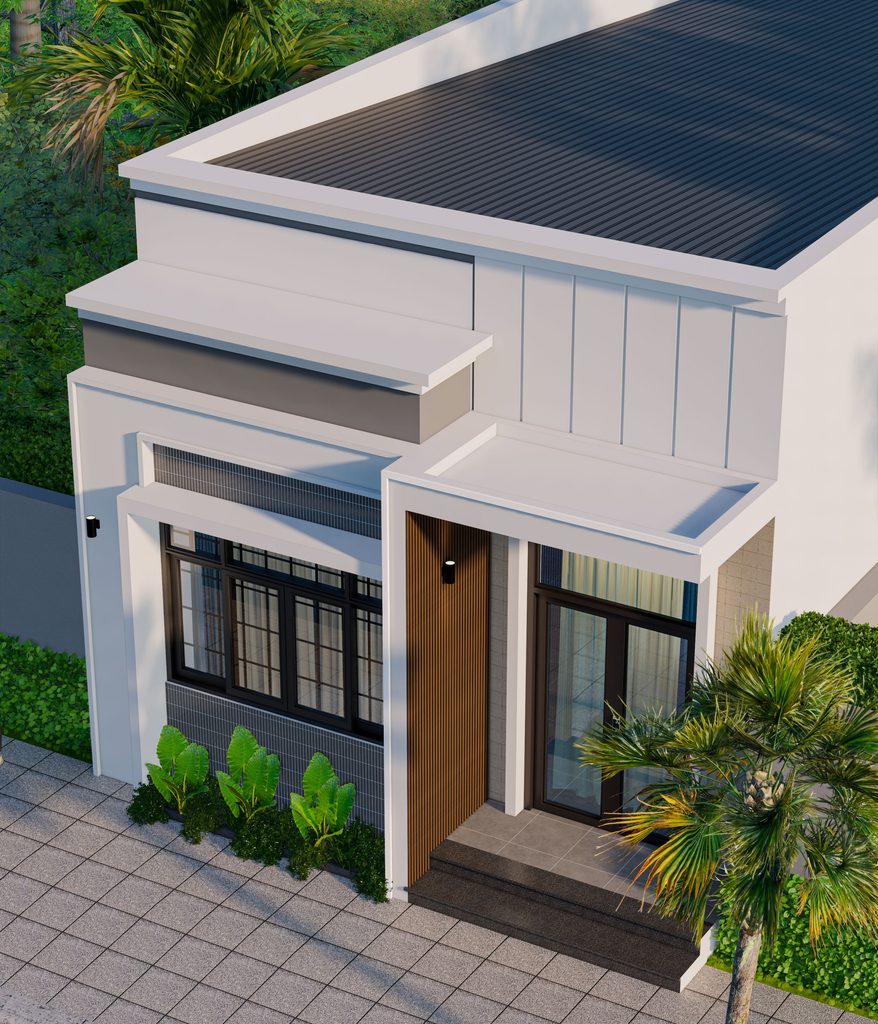
A spacious apartment can also become a source of income. Anyone who buys a 2 BHK or larger unit keeps the option of earning passive income from it. In thriving residential corridors, rental demand consistently outstrips supply. An owner can therefore lease out a spare room, or the whole unit if circumstances require a move, and turn a personal asset into a dependable earner.
Financial habits benefit as well. Servicing a structured home loan demands discipline and builds it. Paying on time every month is among the fastest ways to establish a strong credit history. An excellent credit score raises overall financial credibility and can unlock lower interest rates on future loans, credit cards, and business ventures. The budgeting routine that homeownership requires tends to carry over into every other part of a person’s finances.
The expert also stresses what the spreadsheet cannot capture. Owning a home brings a sense of belonging, pride, and psychological safety that renting cannot replicate. Families who must relocate every few years, whether because a lease was not renewed or because rent jumped suddenly, face disruption at home and in their children’s schooling. An owner becomes a permanent part of the neighborhood, puts down roots, builds lasting relationships with neighbors, and escapes the stress of short-term rental agreements.
Control over the space itself is another point. Tenants live under a steady list of restrictions. They cannot paint the walls their favorite color, remove a non-structural partition to Improve the layout, or install high-end fixtures without risking the security deposit or running into the landlord’s refusal. An apartment owner has full freedom to redesign the interior, upgrade kitchen appliances, lay premium flooring, and tailor every square inch to personal taste and daily needs, all of which maximizes comfort.
Modern urban apartments, he adds, deliver a complete lifestyle ecosystem rather than four walls. Gated communities and luxury developments offer landscaped parks, fully equipped fitness centers, swimming pools, clubhouses, and children’s play areas. Standalone rental houses and older properties cannot match these shared facilities for everyday quality of life.
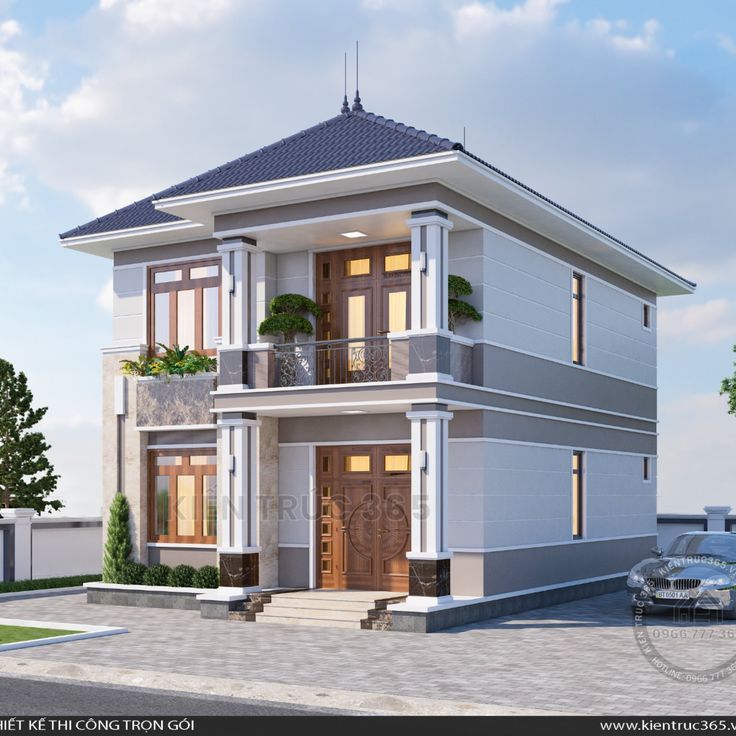
Safety is a leading concern for families today, and standalone rental houses often lack comprehensive protection. Premium apartment complexes, by contrast, layer their security with gates manned around the clock, CCTV surveillance, intercom systems, and restricted visitor access. That environment gives families total peace of mind, lets children play freely, and allows for restful nights.
Four common questions round out the case. Asked why buying beats renting, he answers that buying offers long-term equity, asset appreciation, stability, and complete freedom to customize, while renting is an ongoing sunk cost with zero return on investment. Asked about the biggest single advantage of buying, he names ownership equity: monthly payments build a valuable asset that appreciates over time instead of disappearing into someone else’s pocket. On the main advantages of apartments, he lists superior security, shared community amenities, lower individual maintenance costs, and a convenient, connected lifestyle. And on why apartment living is superior to independent houses, he says residents gain access to upscale shared facilities such as fitness centers and parks, without the heavy burden and cost of exterior maintenance and standalone security management.
His conclusion is that moving from tenant to homeowner remains one of the most powerful wealth-building decisions a person can make. An apartment purchase brings unmatched financial security, protection against inflation, tax advantages, and a far better quality of life. Whether the goal is a dream residence or a high-potential investment property, owning real estate secures long-term stability and prosperity. The message comes from Siddhi Homes, which says it specializes in building premium living spaces engineered for comfort, safety, and exceptional future appreciation, and invites buyers to explore its latest portfolio of projects as a first step toward a home that truly belongs to them.
To sum up the argument: rent payments leave and never return, while mortgage payments build equity, lock in costs, qualify for tax benefits, and open the door to rental income, stronger credit, a safer community, and a home shaped entirely by its owner.
If you found this breakdown useful, hit the subscribe button so you don’t miss what comes next. Give the video a like if it helped, and turn on the notification bell to get our latest reports the moment they go live.”