Condominiums and other multi-family homes have long carried an unfair label in the housing market: the consolation prize for buyers who could not land a house.
The assumption is that a home stacked inside a larger building forces a trade among privacy, room to spread out, and independence. Part of that is accurate. A high-density property cannot offer the wide backyard of a suburban estate. Yet city living is quickly turning into a first-choice lifestyle for today’s buyers. Someone with ten years in the real estate industry can lay out what condo ownership really involves, how it affects your finances, and which questions deserve answers before you commit.
Start with what draws buyers in. Six benefits come up again and again.
Price is the first. For people who live in cities and for young professionals, an apartment or townhouse is a much cheaper doorway into owning property. Industry data repeatedly shows that first-time buyers regard condos as a sensible way onto the first rung of the property ladder. Because these homes sell for less than detached single-family houses, a buyer can hold a deed earlier, begin building equity, and settle in a prime metropolitan area where a traditional house is simply beyond the budget.
Location is the second. Real estate value has always followed location, and condominiums dominate the urban core. A vertical home puts you within walking distance of financial districts, cultural hubs, fine dining, and public transit networks. Shorter commutes and entertainment close at hand sharply Improve how efficiently a day runs, turning hours once lost in transit into personal or professional productivity.
Upkeep is the third. Living in a vertical home removes the weekend routine of mowing the lawn, clearing the gutters, and repainting the exterior. Units have less square footage, and the common elements are managed by a homeowners association, or HOA, so routine maintenance shrinks dramatically. Busy executives, frequent travelers, and anyone who wants their weekends back stand to gain the most. Monthly HOA dues pay for exterior management, which keeps the structure sound and the grounds in top condition without any hands-on labor from individual owners.
Right-sized space is the fourth. Single professionals and young couples often find a condominium to be an ideal footprint, with functional, well-designed square footage and none of the burden that comes with sprawling multi-room estates. Contemporary architecture squeezes the most from every foot, with clever storage solutions, open-plan kitchens, and comfortable living zones. The layout appeals to people who prize efficiency, minimal clutter, and a streamlined home over guest rooms that sit empty.
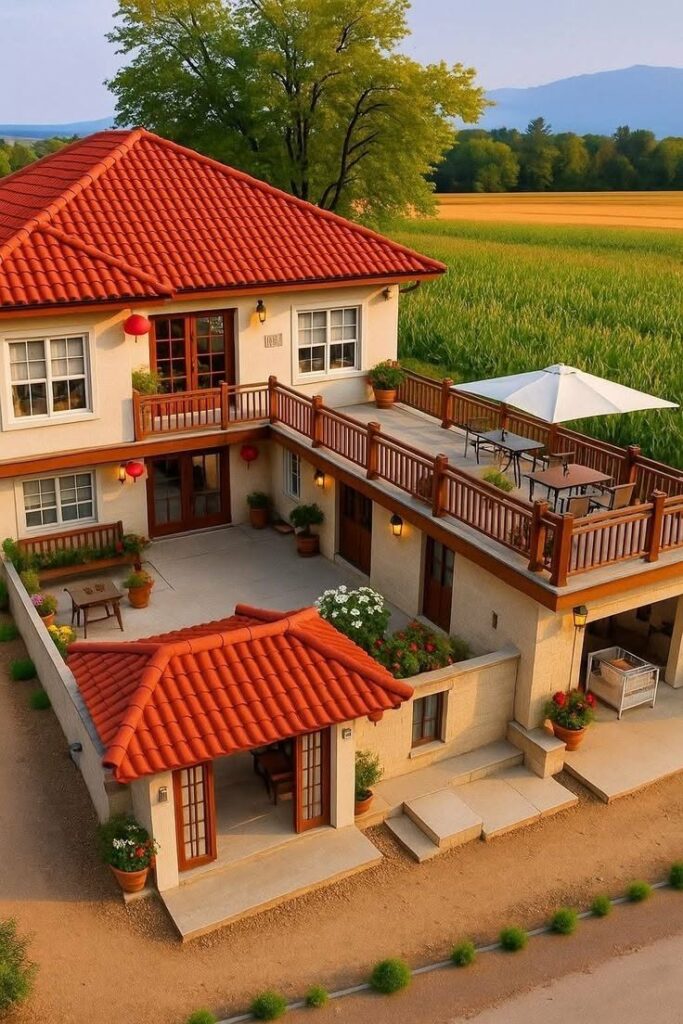
Amenities are the fifth. Modern multi-family complexes frequently include lifestyle perks that would cost a fortune to maintain in a private home. Depending on the development, residents may have access to fitness centers open around the clock, private parking structures, rooftop terraces, secure storage lockers, and swimming pools. These shared assets lift everyday life and nurture an active, lively community right outside the front door, while individual owners are spared the work of maintaining them.
Security is the sixth, and it ranks high on the priority list of urban residents. Multi-family buildings perform especially well here. Most developments use secure perimeter access, electronic key fobs, intercom systems, and carefully placed surveillance cameras. That controlled-entry setup means only residents and authorized visitors get onto the premises. Solo occupants, and people who lock up and leave for long stretches, gain considerable peace of mind.
Now to the other side of the ledger. Seven considerations deserve attention before any offer goes in.
First, understand how ownership is structured. Condominiums are typically held under unit title or strata ownership, which means you own the deed to your specific dwelling space along with designated accessory units, such as a storage locker or a garage stall. Parking spaces and additional storage, however, are sometimes separated from the primary title and must be bought or leased on their own. Confirming the exact boundaries and the assets that are included helps you avoid unexpected out-of-pocket costs later.
Second, recognize that buying a unit automatically makes you a member of the building’s management association, known as an HOA or body corporate. Members pay regular dues that cover shared insurance, property management, contributions to the capital reserve, and services such as waste management. Reviewing the association’s financial health, its governance rules, and its meeting minutes is not optional. Those records show whether upcoming capital expenditures or special assessments could catch your personal budget off guard.
Third, study the building’s long-term capital maintenance plan. Before you finalize an offer, look at the capital reserve fund and the schedule of past maintenance. A well-funded reserve points to proactive governance and protects owners from sudden special levies for major repairs such as roof replacements or elevator overhauls. A structurally sound building also protects your long-term equity and the stability of your investment.
Fourth, audit the property insurance. The building’s master insurance policy needs a close read. Confirm that it covers catastrophic events, that the association’s accounts are independently audited, and that the property faces no ongoing structural litigation or weather-tightness problems. Adequate coverage keeps your investment shielded from unforeseen structural liabilities.
Fifth, read the bylaws, rules, and usage restrictions. Association bylaws set the standards for daily life, governing pet ownership policies, noise ordinances, short-term rental rules, and architectural modifications. Read these restrictions closely to make sure they fit both your lifestyle and your long-term investment goals. If you intend to lease the property out someday, for instance, current rental caps could affect your strategy.
Sixth, weigh the acoustics and the level of privacy. Living close to your neighbors calls for a careful look at sound insulation and at who lives in the community. Some buildings foster a warm, tight-knit atmosphere, while others see high tenant turnover. Visiting during peak evening hours or on a weekend gives you an accurate sense of ambient noise and overall privacy.
Seventh, consider the age of the building and its engineering reports. A structure’s age directly shapes its maintenance profile. Newer buildings come with modern finishes but can occasionally conceal construction defects, while older buildings have proven engineering histories but may need updating. Commissioning an independent property inspection report gives you a clear view of construction quality, material wear, and future capital requirements.
Taken together, the case for a condominium rests on lower entry prices, less upkeep, efficient space, shared amenities, layered security, and a central location, balanced by the homework a buyer owes to ownership structure, association finances, insurance, rules, noise, and the condition of the building. Weighing both columns honestly shows whether vertical living fits your own financial goals and daily routine.
If this breakdown helped you size up the condo market, hit the subscribe button so you don’t miss the next video. Give the video a like if you found it useful, and turn on the notification bell to catch our latest reports the moment they go live.”