Renting vs Buying a Home: Is Now the Right Time to Make Your Move?
Navigating the timeless crossroad of renting versus buying a home is a milestone that nearly everyone faces at some point in their journey. Over my past decade working directly in the real estate sector, helping hundreds of clients evaluate their portfolios and lifestyle needs, this remains one of the most frequent dilemmas brought to the table. Market shifts, interest rate fluctuations, and changing personal goals mean the calculus is constantly evolving. In this comprehensive guide, we will break down the true advantages of both paths through an expert lens, evaluating current market dynamics to help you determine if today is the right time to transition or stay put.
The Strategic Advantages of Renting
While homeownership often steals the spotlight in cultural conversations, renting offers distinct structural and financial advantages that should never be underestimated, especially in today’s economic climate.
Superior Financial Flexibility
One of the most compelling perks of renting is the high degree of financial fluidity it preserves. By choosing a lease over a purchase, you sidestep the massive capital drain of assembling a substantial down payment, avoiding immediate out-of-pocket hits for property taxes, homeowners insurance, and transfer fees. This leaves your capital free to be deployed elsewhere—whether that is building a diversified investment portfolio, funding a business venture, or maintaining a robust emergency fund.
Mitigated Maintenance and Repair Burdens
As a tenant, you are entirely shielded from the unpredictable and often staggering costs of physical upkeep. When a plumbing line bursts, a roof requires structural repair, or an HVAC unit fails, the financial and logistical burden falls squarely on the landlord. Over a multi-year lease term, this lack of hidden maintenance expenses can save you thousands of dollars and eliminate a significant amount of stress.
Unmatched Geographic Mobility
Life moves quickly, and career trajectories or family structures can pivot overnight. Renting offers unmatched agility if you are uncertain about your long-term zip code. Packing up and moving at the end of a lease cycle is infinitely simpler, faster, and cheaper than listing a property, paying realtor commissions, and navigating a complex real estate closing.
The Compelling Benefits of Buying a Property
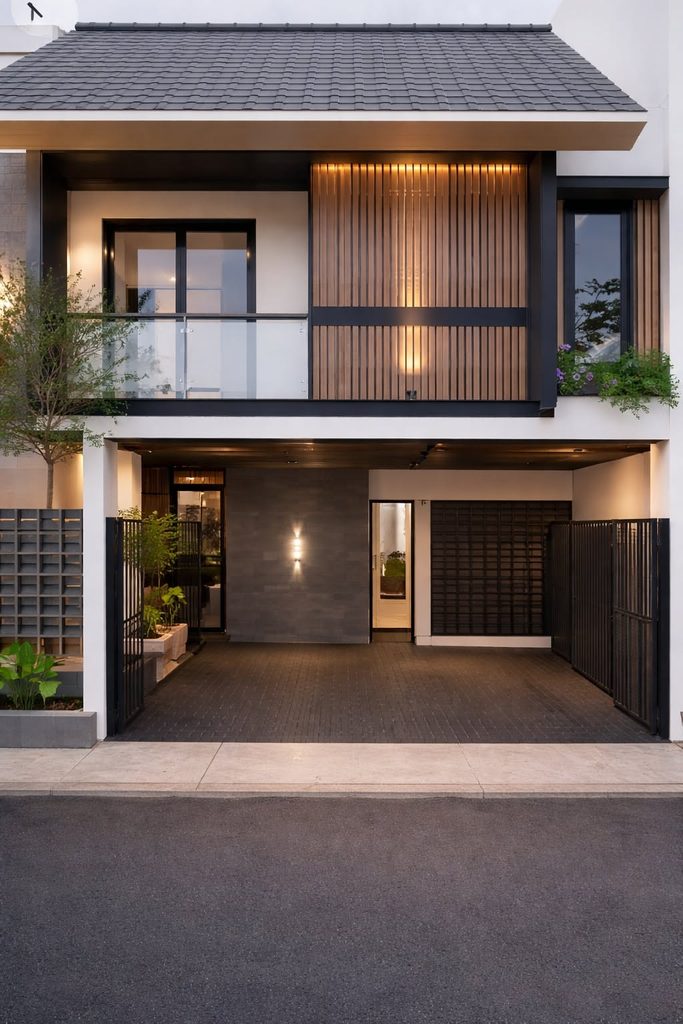
On the flip side, purchasing real estate remains a cornerstone of long-term wealth building for millions. Let us examine why buying continues to hold massive structural appeal.
Equity Accumulation and Forced Savings
Every mortgage payment you make functions as a form of forced savings, systematically chipping away at the principal balance while building long-term equity. Over years and decades, this ownership stake transforms into a substantial financial asset, providing a bedrock for your net worth that renting simply cannot replicate.
Absolute Stability and Creative Control
Owning your home grants you total autonomy over your living environment. You are entirely immune to unexpected rent hikes, lease terminations, or landlords deciding to cash out and sell the property. Furthermore, you have the absolute freedom to renovate, remodel, and customize your space to match your exact aesthetic and functional preferences without needing anyone’s permission.
Long-Term Value Appreciation
Historically, residential real estate has demonstrated a strong tendency toward steady long-term appreciation. Buying a home allows you to leverage your capital, meaning a relatively modest down payment secures an asset that grows in total market value over time, compounding your returns far beyond standard liquid savings accounts.
Is Now the Right Time to Buy a Home?
With the pros and cons laid out, the central question persists: should you pull the trigger on buying right now? Making this choice successfully requires looking past the noise and evaluating a few foundational pillars.
Evaluating Your Financial Readiness
Before entering the market, you must run an honest audit of your financial stability. Do you maintain a predictable, reliable income? Is your credit score optimized to secure competitive mortgage rates? Can you comfortably service a monthly mortgage payment alongside other debt obligations and everyday living expenses without living paycheck to paycheck? If your financial house is in order, exploring homeownership is a logical next step.
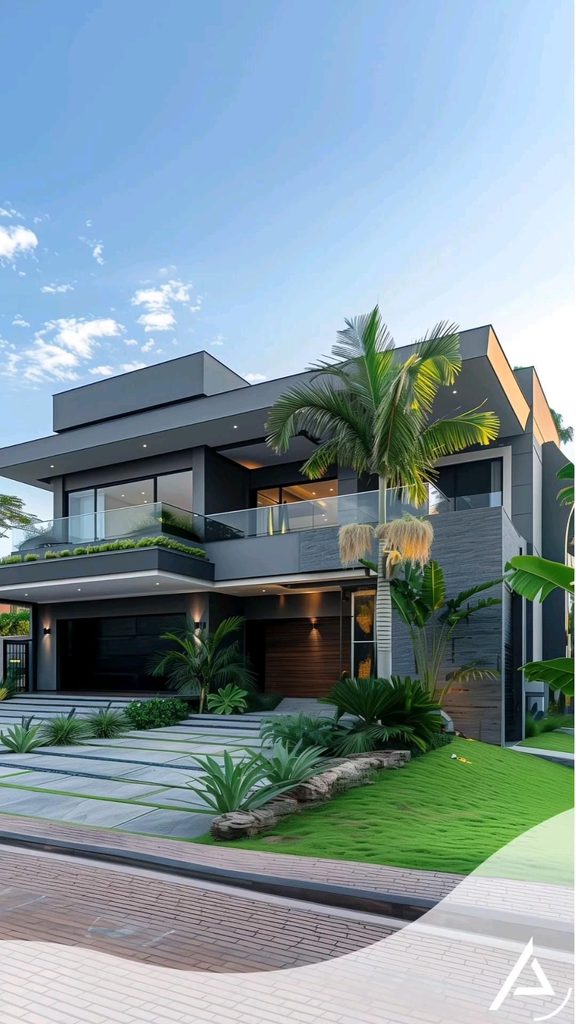
Analyzing Current Market Conditions
Real estate cycles dictate strategy. In a balanced or buyer-driven market with higher inventory, you enjoy more negotiating leverage, inspection contingencies, and potentially seller concessions. Conversely, a tight market characterized by low inventory requires aggressive positioning, rapid decision-making, and strong financial backing. Consulting with an experienced local real estate professional is vital to decoding these hyper-local micro-trends.
Mapping Your Long-Term Horizon
Real estate is fundamentally an illiquid asset that rewards patience. If your personal or professional situation is volatile, buying might tie your hands prematurely. However, if you plan to plant roots in a specific area for the next five to seven years, purchasing a home transforms from a short-term gamble into a stable, wealth-building strategy.
Down Payment, Affordability, and Lending Options
Take a meticulous look at your liquid assets to determine your comfort level regarding down payments and closing costs. While aiming for a conventional 20% down payment helps you avoid private mortgage insurance (PMI), numerous modern loan programs cater to buyers with lower upfront thresholds. The key is understanding the lifetime cost of borrowing under each scenario.
Factoring in Ongoing Property Ownership Costs
First-time buyers often underestimate the total cost of homeownership. Beyond the mortgage, you must budget for property taxes, municipal fees, hazard insurance, and routine maintenance—typically recommended at 1% to 2% of the home’s value annually. Ensuring you have a dedicated buffer for these expenses prevents lifestyle creep from turning into financial stress.
Making Your Ultimate Decision
Ultimately, the choice between renting and buying is deeply personal, heavily dependent on your unique life stage, risk tolerance, and financial architecture. There is no universal formula; what represents financial wisdom for one person may be a liability for another.
If you find yourself at a crossroads and want absolute clarity tailored to your unique financial situation, let us connect. Schedule a complimentary consultation with our advisory team today, and let us map out a customized real estate strategy to secure your financial future.