Navigating Renting vs Buying a Home: Is Now the Right Time to Make Your Move?
For over a decade working as a real estate advisor, I have watched individuals and families grapple with one of life’s most significant financial crossroads: should you keep renting or step onto the property ladder? It is a classic dilemma that resurfaces whenever personal milestones shift or market conditions fluctuate. Deciding between renting vs buying a home goes far beyond simple math; it shapes your lifestyle, your financial trajectory, and your peace of mind.
To help you decode this complex decision with confidence, we need to dissect the real-world advantages of both paths, evaluate current housing market trends, and pinpoint how to figure out if today is genuinely the right moment for you to buy a home.
The Strategic Advantages of Renting
Many prospective buyers overlook the immense strategic value that renting can offer, particularly when life is in flux or capital needs to be preserved for higher-yield opportunities.
Superior Financial Flexibility
Choosing to rent a home grants you a high degree of liquidity. You bypass the grueling process of saving for a massive deposit, and you completely sidestep upfront ancillary expenses like property taxes, building insurance, and council rates. This means your capital remains free to invest in your business, stocks, or high-yield savings accounts, rather than being locked up in concrete.
Predictable and Lower Maintenance Responsibilities
One of the most liberating aspects of renting a home is shedding the burden of property upkeep. When a plumbing line bursts or a storm damages the roof, the financial and logistical headache belongs squarely to the landlord. Over a decade of managing properties, I have seen unexpected repairs drain thousands of dollars from unprepared homeowners—an expense renters never have to shoulder.
Unmatched Mobility and Lifestyle Freedom
If your career requires frequent relocation, or if you are still figuring out which neighborhood suits your lifestyle best, renting offers unmatched geographical freedom. Packing up and moving when a lease expires is infinitely simpler, faster, and less costly than navigating the traditional home selling process, dealing with real estate commissions, and waiting for property market clearance.
The Long-Term Benefits of Buying a Home
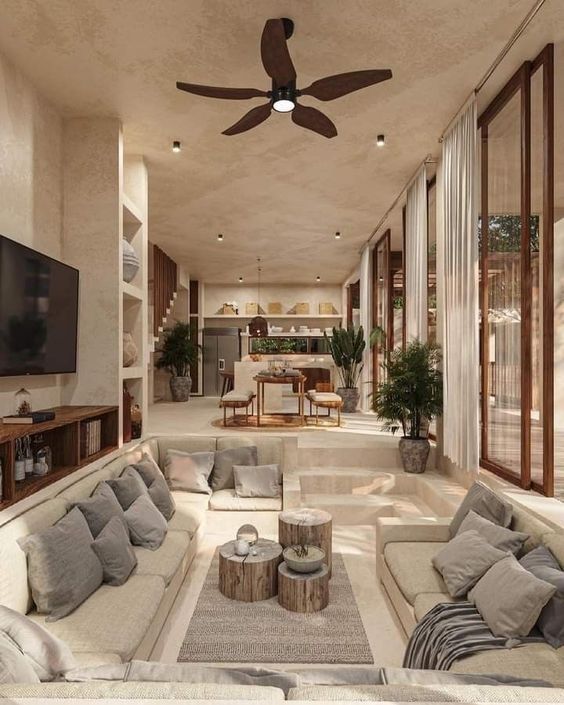
While renting offers flexibility, buying a home remains the cornerstone of generational wealth building for millions of households.
Ownership, Equity Building, and Forced Savings
When you purchase a property, every monthly mortgage payment functions as a form of forced savings. Instead of pouring money into a landlord’s pocket, you are steadily building equity—your personal stake in a tangible asset. Over years of consistent ownership, this equity transforms into a powerful financial cushion.
Stability, Autonomy, and Customization
Owning your home shields you from sudden rent hikes, lease terminations, or landlords deciding to cash out and sell the property. Beyond financial security, homeownership delivers total creative control. You can renovate the kitchen, knock down walls, landscape the backyard, and truly customize your living environment to match your aesthetic and functional needs.
Capital Growth in Property Markets
Historically, real estate markets across New Zealand have demonstrated resilient long-term capital growth. Property values tend to appreciate over extended horizons, making a well-chosen residential property an attractive cornerstone investment that often outperforms inflation.
Is Now the Right Time to Buy a Home?
Weighing the pros and cons is only the starting point. The million-dollar question remains: is now the right time to buy a home? To arrive at an objective answer, you must evaluate several vital markers.
Assessing Your Financial Stability and Debt-to-Income Ratio
Before diving into the property market, take a rigorous inventory of your financial health. Do you maintain a steady, reliable income stream? Is your credit score in excellent shape? Can you comfortably cover a monthly mortgage payment alongside other living expenses without living paycheck to paycheck? If your financial foundation is rock solid, exploring how to buy a home is a sound next step.
Analyzing Local Housing Market Conditions
Market dynamics change rapidly. In a buyer’s market characterized by ample inventory, you have more leverage to negotiate purchase prices and secure favorable terms. Conversely, a competitive seller’s market demands swift action, competitive offers, and meticulous preparation. Tracking local market trends alongside a seasoned real estate agent ensures you do not overpay.
Evaluating Long-Term Personal and Career Plans
Real estate is an illiquid asset that requires a multi-year commitment to yield favorable returns. If you plan on staying in the area for at least five to seven years, buying a home makes profound financial sense. However, if your career or family dynamics are uncertain, maintaining the agility of renting might be the wiser short-term strategy.
Down Deposit and Affordability Metrics
Evaluating your deposit capacity is critical. While a 20% down payment traditionally helps you secure the best mortgage rates and avoid lenders’ mortgage insurance, various low-deposit home loan options exist. Ensure you map out closing costs, legal fees, and moving expenses so you are never caught financially overextended.
Anticipating Future Lifestyle Goals
Your personal aspirations should heavily dictate your housing strategy. If homeownership represents a core pillar of your future security, taking the plunge aligns your actions with your vision. If you value minimalism and flexibility above all else, continuing to rent allows you to optimize your lifestyle without property ties.
Making Your Final Decision
Ultimately, the choice between renting vs buying a home is deeply personal, heavily influenced by individual circumstances, risk tolerance, and economic climate. There is no universal formula that dictates what is right for everyone.
Take the time to consult with an independent financial advisor or a trusted real estate expert to run the numbers based on your specific financial portfolio. When your personal readiness intersects with favorable market timing, making your move becomes an empowering step forward.
If you are ready to evaluate your options, analyze current mortgage rates, or map out your path to homeownership, reach out today to schedule a personalized consultation and take the next step toward your future.