End of the Road: Why the Polestar U.S. Sales Ban Signals a New Era for Global Auto Markets
Over my ten years navigating the intricate intersection of global automotive strategy and international trade policy, I have rarely witnessed a regulatory pivot as absolute—and as consequential—as the Polestar U.S. sales ban. For the Swedish-born, Chinese-backed electric vehicle manufacturer, the American dream is effectively over before it ever reached critical mass. Following intense dialogues with government officials, the brand has officially decided against appealing the Polestar U.S. sales ban, essentially confirming its retreat from the stateside market and marking a dramatic pivot toward its European home turf.
This isn’t merely a minor roadblock for a niche luxury automaker. The Polestar U.S. sales ban serves as the ultimate cautionary tale for the entire automotive industry. It perfectly illustrates how geopolitical tensions, supply chain intricacies, and stringent new software regulations are redrawing the map for global automakers. As we dissect the anatomy of the Polestar U.S. sales ban, we uncover a much larger narrative about the future of global trade, consumer impact, and the complex reality of building the cars of tomorrow.
Decoding the Regulatory Hammer: The Connected Vehicle Rule
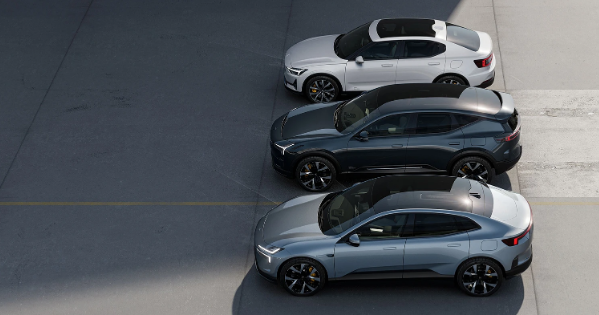
To truly understand the inevitability of the Polestar U.S. sales ban, we have to look closely at the regulatory framework that triggered it. In early 2025, the U.S. Department of Commerce—specifically through the Bureau of Industry and Security (BIS)—finalized the Connected Vehicles Rule. This sweeping legislation fundamentally altered the landscape of US Commerce Department EV restrictions by strictly prohibiting the import and sale of vehicles equipped with connected hardware or software linked to “foreign adversaries,” namely China and Russia.
The rationale behind the legislation is rooted deeply in national security. Modern electric vehicles are essentially rolling supercomputers. They rely heavily on Vehicle Connectivity Systems (VCS) and Automated Driving Systems (ADS) that utilize advanced telematics, multiple high-definition cameras, GPS arrays, and cellular modules. The Commerce Department determined that these systems pose an unacceptable national security risk due to their potential for data harvesting, surveillance, or even remote sabotage.
Because Polestar is majority-owned by China-based Geely Auto, it fell squarely in the crosshairs of these automotive cybersecurity regulations. Even though Polestar is headquartered in Gothenburg, Sweden, and heavily markets its Scandinavian design heritage, the underlying architecture, software development, and corporate governance are inextricably linked to Geely. As a result, the Polestar U.S. sales ban became unavoidable when the company could not strip the scrutinized Chinese software out of its 2027 model-year vehicles in time to meet the rigorous standards of connected vehicle software compliance.
The Geely Dilemma and the Volvo Exception
One of the most fascinating aspects of the Polestar U.S. sales ban is the stark contrast with its corporate sibling, Volvo. Both companies operate under the Geely umbrella, yet they have met entirely different fates in the American market. Why did Volvo manage to secure an authorization to continue its stateside operations in May, while its sister brand was suffocated by the Polestar U.S. sales ban?
The answer lies in the deeply granular nuances of automotive supply chain risk management. Volvo, possessing a much larger historical footprint and a highly localized manufacturing ecosystem in the United States, was able to pivot its software sourcing and demonstrate a firewall between its U.S. operations and its Chinese parent company. Volvo meticulously provided the necessary Software Bill of Materials (SBOMs) to prove their North American fleet met the strict new compliance mandates.
Polestar, on the other hand, operates on a much leaner, highly integrated global model that relies heavily on Geely’s shared platforms and software stacks. Even though the brand made strategic moves to build outside of China—assembling the Polestar 3 at Volvo’s plant in Charleston, South Carolina, and moving production of the new Polestar 4 to Busan, South Korea—the physical assembly location was ultimately irrelevant under the law. The rule targets the origins of the intellectual property, the code, and the connective hardware, not just the final point of assembly. The inability to decouple these critical technological components fast enough cemented the finality of the Polestar U.S. sales ban.
What the Polestar U.S. Sales Ban Means for Consumers
If you are a current owner, the immediate headlines surrounding the Polestar U.S. sales ban might seem terrifying, but the reality is much more stabilized. The company has explicitly stated that supporting its existing customer base remains its highest priority. The regulation specifically prohibits the marketing and sale of new vehicles from the 2027 model year onward. This means the existing inventory of Polestar 3 and Polestar 4 models currently on American soil will be sold until supplies are depleted.
More importantly, all existing warranties remain in full effect. Current owners and lessees will continue to have access to service networks, over-the-air updates for existing approved software, and ongoing maintenance support. However, from an ownership perspective, the long-term ripple effects of the Polestar U.S. sales ban will undoubtedly alter the financial viability of holding these vehicles.
First, consider the secondary market. A brand exiting a major region almost always triggers a steep depreciation curve for its existing fleet. For those currently exploring luxury electric vehicle lease deals, acquiring a soon-to-be-discontinued model might come with incredibly aggressive incentives as dealers desperately try to clear out remaining inventory. However, buyers should proceed with extreme caution. The residual values of these vehicles will likely plummet, making traditional purchasing risky.
Furthermore, we must look at the impact on electric vehicle financing deals. Lenders evaluate risk based on the long-term value and support network of the underlying asset. With the manufacturer ceasing new vehicle sales, banks and credit unions may adjust their loan-to-value requirements or raise interest rates on Polestar models to offset the risk of financing an orphaned brand.
Then there is the critical issue of EV auto insurance. Actuaries price insurance premiums based on repairability, parts availability, and historical safety data. With the Polestar U.S. sales ban halting the influx of new parts channels and dealership expansions, the cost to repair these highly specialized, sensor-heavy vehicles is expected to climb. Consequently, current and future owners should anticipate noticeable increases in their EV auto insurance premiums over the next three to five years as the stateside supply chain for replacement parts inevitably constricts.
The Ripple Effect on Commercial Fleets
Beyond the retail consumer, the Polestar U.S. sales ban has severely disrupted the commercial sector. Over the past few years, we saw Polestar actively courting the rental and corporate fleet markets, partnering with major players like Hertz to integrate their stylish EVs into mainstream travel.
Corporate fleets rely heavily on predictable total cost of ownership (TCO) models, robust servicing agreements, and advanced EV fleet management solutions that integrate telematics data for tracking efficiency and vehicle health. The implementation of strict automotive cybersecurity regulations means that commercial entities are now highly scrutinized regarding the software embedded in their fleet vehicles. The Polestar U.S. sales ban forces fleet managers to rapidly pivot away from the brand to avoid compliance violations and unmanageable depreciation risks. Competitors with localized software development—such as Tesla, Rivian, and traditional legacy automakers—are already absorbing the market share that Polestar is being forced to leave behind.
Pivoting Across the Atlantic: The European Strategy
While the Polestar U.S. sales ban is a massive blow to the company’s global prestige, it is not necessarily a fatal wound. According to first-quarter financial data from 2026, a staggering 94 percent of Polestar’s global sales originated outside of the United States. The American market, while highly lucrative and critical for brand valuation, was already proving to be a fiercely challenging environment characterized by extreme pricing pressures, cooling consumer demand for premium EVs, and the heavy burden of imported EV tariffs.
Faced with the insurmountable hurdle of the Polestar U.S. sales ban, the automaker is officially shifting its full strategic weight to Europe. The European market presents a fundamentally different landscape. While the EU has recently implemented its own set of tariffs on Chinese-made electric vehicles, their regulatory framework regarding connected vehicle software is currently focused more heavily on data privacy (GDPR compliance) rather than the strict national security embargoes seen in the United States.
By retreating from America, Polestar can consolidate its resources, streamline its marketing budgets, and aggressively target the European consumer base that already embraces the brand’s minimalist aesthetic and sustainability ethos. This pivot allows them to navigate around the immediate fallout of the Polestar U.S. sales ban and focus on defending their market share against the influx of domestic Chinese brands—like BYD and Nio—that are currently flooding the European continent.
The Tragic Loss of the Polestar 6
From an enthusiast’s perspective, the most heartbreaking casualty of the Polestar U.S. sales ban is the loss of the brand’s future pipeline, specifically the highly anticipated Polestar 6. Slated as a halo vehicle, the Polestar 6 is a breathtaking, hardtop convertible electric roadster designed to rival the likes of the Porsche 911 and the long-delayed Tesla Roadster. It promised 884 horsepower, an 800-volt architecture, and a zero-to-sixty time under three seconds.
For the American automotive enthusiast, the Polestar 6 represented a bold new direction for the EV market—a shift away from bulky, utilitarian SUVs toward pure, electrified driving passion. Unfortunately, because this model falls well past the 2027 regulatory cutoff, the Polestar U.S. sales ban guarantees that this striking piece of automotive engineering will never grace the Pacific Coast Highway or carve through the canyons of Malibu. It will remain forbidden fruit, admired from afar by American drivers while European and Asian markets reap the benefits of Geely’s performance division.
Looking Ahead: The New Blueprint for Automakers
In my professional estimation, the Polestar U.S. sales ban is merely the opening salvo in a much broader geopolitical tech war that is reshaping the automotive industry. We are witnessing the end of the unfettered, hyper-globalized auto market. The era where a car could be designed in Sweden, funded in China, assembled in South Korea, and sold freely in California is rapidly coming to a close.
The Polestar U.S. sales ban proves that software is the new battleground. Moving forward, every single original equipment manufacturer (OEM) will have to master the art of automotive supply chain risk management on a microscopic level. It is no longer just about sourcing lithium for batteries or securing stamping facilities; it is about tracking every single line of code, every open-source dependency, and every piece of middleware running on the vehicle’s network.
To avoid falling victim to their own version of the Polestar U.S. sales ban, automakers must embrace radical transparency. We will see a massive surge in demand for localized software development hubs in North America and allied nations. The focus on connected vehicle software compliance will become just as critical as crash test safety ratings.
Furthermore, the Polestar U.S. sales ban is a wake-up call for regulators and industry leaders to collaborate more effectively. The swiftness of this regulatory action caught many off guard, demonstrating that governments are fully willing to sacrifice market competition in the name of national security. As vehicles continue to evolve into autonomous, hyper-connected digital ecosystems, the invisible borders of software regulation will dictate the physical borders of auto sales.
The Polestar U.S. sales ban is a definitive, historic turning point. It highlights the stark realities of the modern global economy, where the origins of a vehicle’s code are scrutinized far more harshly than the origins of its steel. Polestar will undoubtedly survive this ordeal by leaning heavily into its European and Asian strongholds, but its absence in the United States leaves a noticeable void in the premium EV sector—a void that domestic and compliant legacy brands are eager to fill.
As the dust settles on this monumental regulatory shift, industry professionals and consumers alike must adapt to this new normal. If you are navigating the complexities of the modern EV landscape—whether you are a fleet manager trying to optimize your operational compliance, an executive restructuring your component sourcing, or simply a consumer trying to understand how these global shifts affect your next vehicle purchase—staying ahead of the curve is no longer optional. I invite you to subscribe to my weekly automotive insights newsletter, where we continuously decode the rapidly evolving intersection of electric mobility, global trade policy, and automotive technology, ensuring you are never caught off guard by the next major industry disruption.