Every month, a housing payment leaves a person’s bank account, and it ends up in one of two places.
It either vanishes into a landlord’s pocket or it builds something the payer gets to keep. That single distinction sits at the center of the rent-versus-buy debate. I have worked in real estate for more than ten years and have advised hundreds of people who could not decide between the two. The subject stirs strong emotions and carries serious financial weight. Yet in rising markets and falling ones alike, the math has pointed the same way. For anyone who wants lasting financial footing and genuine security, buying an apartment is by far the smarter move. Interest in modern city housing keeps growing, and more buyers each year understand why owning outperforms renting. Property is the stronger investment. It offers security for life, steady and predictable finances, and wealth a person can see and touch.
Consider the money first, because that is where the two paths split most sharply. Buying real estate is a strategic, long-term investment that builds equity steadily over time. Rent works on different logic. Each payment goes to the landlord as an ongoing operating expense, and the tenant gets nothing back for it. Ownership functions more like a forced savings plan. Every mortgage or EMI payment increases your stake in the property and lifts your personal net worth. Property values have historically climbed over the long run, so the asset gains value year after year. Real estate also serves as a strong hedge against inflation, which lets the original investment compound. A renter watches monthly cash flow drain away and leaves empty-handed when the lease expires.
Rising rents make that gap wider. Landlords have a reputation for pushing rents up at every renewal, which erodes long-term affordability and complicates retirement planning. A home financed with a fixed-rate loan puts housing costs firmly under your control. Home loans bring structured, stable payments, so the arbitrary increases a landlord can Impose never reach you. Landlords raise rents to keep up with inflation, but a fixed housing payment stays anchored. Once the mortgage term finally ends, decades of completely rent-free living follow, which sharply cuts your cost of living in retirement.
Governments tilt the field further. Around the world, they actively encourage homeownership through lucrative tax benefits, and renters miss out on every one of them. Tax laws frequently allow substantial deductions on home loan interest, which lowers the annual tax burden. Portions of the principal repayment can qualify for deductions too, optimizing taxable income even more. Various regional and national schemes for first-time buyers also make entry into the property market more financially accessible than ever.
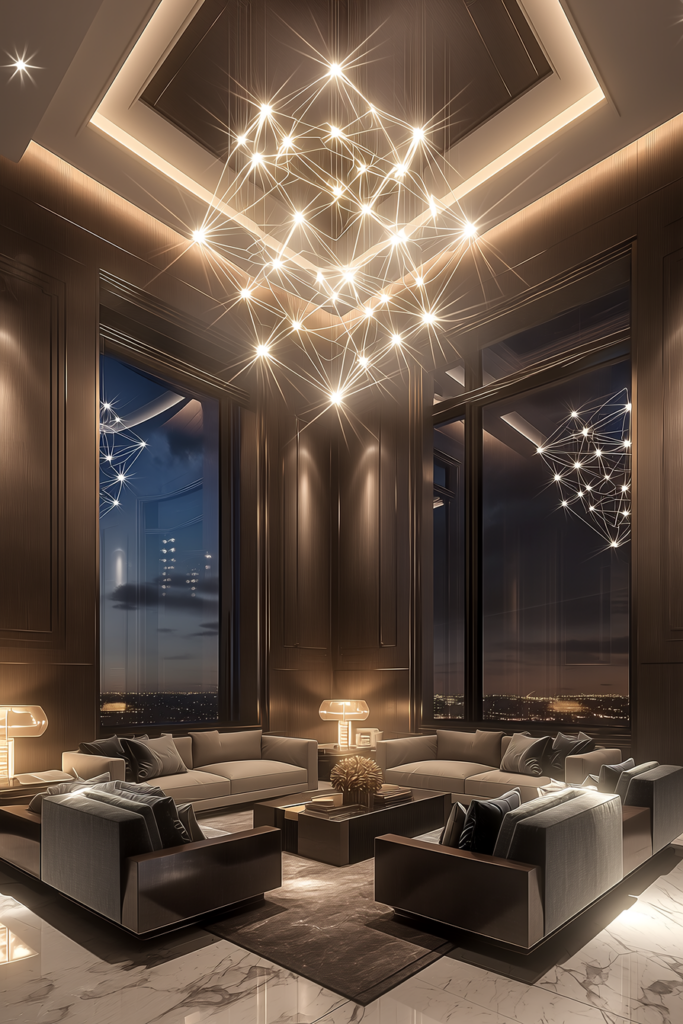
The size of the home adds another lever. Buy a spacious 2 BHK or larger apartment and you keep the flexibility to earn passive income. In thriving residential corridors, rental demand consistently outstrips supply. That robust demand lets you lease out a spare room with ease, or the entire unit if circumstances force you to relocate. Your personal asset then becomes a reliable source of income.
Ownership shapes everyday money habits as well. Managing a structured home loan both requires and fosters ironclad financial discipline. Paying on time each month is one of the fastest ways to build an exceptional credit history, and a pristine credit score strengthens your overall financial credibility. That, in turn, unlocks lower interest rates on future loans, credit cards, and business ventures. The budgeting discipline that homeownership demands spills over into every other corner of personal finance.
Money is only part of the picture, though. Think about what happens when a landlord declines to renew a lease, or when a rent increase arrives with no warning. Few events rattle a household more. Families caught in that cycle may relocate every few years, and each move upsets home routines and interrupts children’s schooling. An owner sidesteps that churn. Owners become fixtures of their neighborhoods, form real bonds with the people next door, and shed the worry that comes with short-term rental agreements. Ownership brings pride, a rooted sense of place, and a psychological security that renting cannot reproduce.
Control over your own space counts for a great deal too. Tenants live under a standing list of restrictions. They cannot repaint the walls in a favorite color, remove a non-structural partition to Improve how a room flows, or install high-end fixtures without risking the security deposit or a landlord’s refusal. An apartment owner faces no such limits. You can overhaul the interior design completely, upgrade the kitchen appliances, lay premium flooring, and tailor every square inch to your own taste and lifestyle, which maximizes your day-to-day comfort.
Modern urban apartments also offer far more than four walls. They deliver an all-encompassing lifestyle ecosystem. Gated communities and luxury developments feature world-class amenities, including landscaped parks, fully equipped fitness centers, swimming pools, clubhouses, and children’s play areas. Standalone rental homes and older properties cannot match the way these shared facilities lift everyday quality of life.
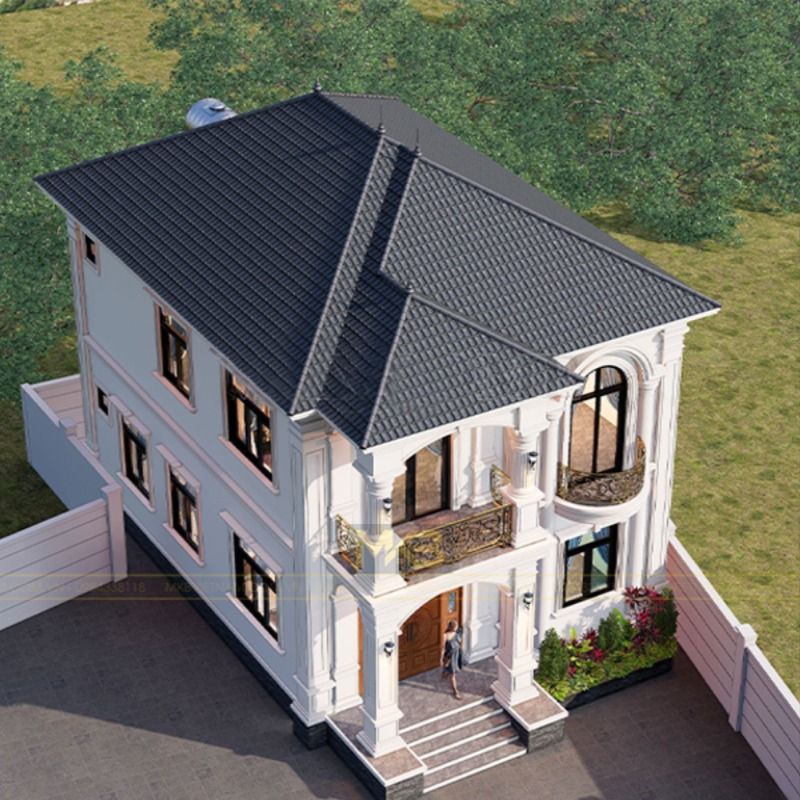
Safety is a primary concern for modern families, and apartments hold the edge there as well. Standalone rental houses often lack comprehensive safety infrastructure. Premium apartment complexes provide multi-tiered security protocols, including 24/7 manned gates, CCTV surveillance, intercom systems, and restricted visitor access. That secure environment offers total peace of mind, letting children play freely and giving parents restful nights.
A handful of questions come up again and again, so here are brief answers. Why is buying a home better than renting? Buying offers long-term financial equity, asset appreciation, stability, and total freedom to customize your space, while renting is an ongoing sunk cost with zero return on investment. What is the single biggest advantage of buying over renting? Ownership equity. Your monthly payments actively build a valuable asset that appreciates over time, rather than vanishing into someone else’s pocket. What are the main advantages of apartments? They provide superior security, shared community amenities, lower individual maintenance costs, and a convenient, connected lifestyle. And why is apartment living superior to independent houses? It grants access to upscale shared facilities such as fitness centers and parks, and it removes the heavy burden and cost of exterior maintenance and standalone security management.
For readers ready to take a first step, Siddhi Homes specializes in crafting premium living spaces engineered for comfort, safety, and exceptional future appreciation. Its latest portfolio of projects is open to explore today, as a definitive first move toward a home that truly belongs to you.
To sum up, moving from tenant to homeowner remains one of the most powerful wealth-building decisions a person can make. An apartment purchase brings financial security, protection against inflation, tax advantages, and a far better quality of life. Whether the goal is a dream residence or a high-potential investment property, owning real estate secures long-term stability and prosperity. The question left for every renter is a simple one: should the monthly payment keep disappearing, or should it start building something?
If this report gave you something to think about, hit the subscribe button so more coverage like it finds its way to you. A quick like helps other viewers discover the video, and switching on the notification bell means the latest stories show up in your feed as soon as they are published.