Across the biggest cities, the buyers filling apartment and condo towers now include many who, not long ago, would have waited for a detached house.
The old assumption treated an apartment as a waiting room, a temporary stop for people still saving toward a roomy suburban home. A decade of guiding clients through city purchases suggests that view has flipped. Dense urban housing no longer reads as a consolation prize. For many buyers, a condo is a deliberate choice about lifestyle and personal finance, and choosing one does not mean surrendering living space. Whether it fits your long-term goals comes down to weighing its genuine advantages against its genuine obligations. The advantages come first.
Location leads the list, and it drives property value. Apartments dominate city centers, so a single unit can place you within walking distance of financial districts, cultural venues, public transit networks, and lively dining scenes. Shorter commutes and nearby errands raise both daily efficiency and overall quality of life.
Price is the second draw. For urban professionals and aspiring homeowners, an apartment or condo offers a far easier entry into the property market, since purchase prices sit well below those of detached single-family dwellings. First-time buyers can shorten a saving period that might otherwise stretch across months or even years, get into the market sooner, and begin building home equity in sought-after central neighborhoods where standalone houses are priced beyond their means.
Security is a priority for many buyers, and multi-family buildings tend to deliver it. Most complexes stack several protections: electronic key fob access, intercom systems, and 24/7 CCTV monitoring, with entry limited to residents and vetted visitors. People who live alone, along with frequent travelers who lock up and leave for long stretches, gain real peace of mind from that controlled setting.
Amenities add another layer. Modern complexes often function as lifestyle hubs, offering high-end features that a standalone home could rarely afford. Residents commonly have fitness centers, private parking structures, rooftop gardens, secure bike storage, and swimming pools within reach. Because these shared facilities put leisure and wellness options steps from the front door, they also foster a vibrant sense of community.
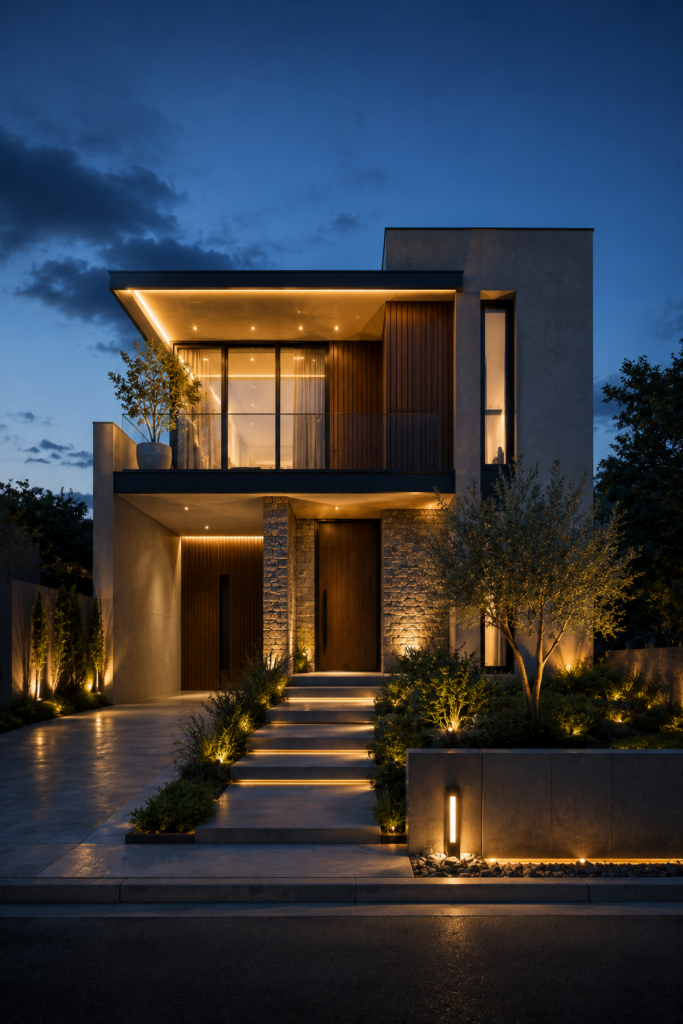
Upkeep shrinks too. A compact floor plan cuts interior cleaning to a fraction of the time, and exterior work such as roof repairs, lawn mowing, and facade painting is handled collectively rather than falling on each owner. Busy, career-driven people, and downsizers who want a low-maintenance routine, get a great deal of time back once those grueling weekend chores disappear.
Space is the last advantage. Single professionals and couples can find ideal square footage in a compact urban unit, free of large yards to maintain or guest rooms that sit empty. Modern architectural design puts heavy emphasis on optimizing layouts, so living zones, kitchens, and storage areas stay functional and comfortable. The streamlined setting also supports a minimalist, clutter-free way of living.
Those gains come attached to obligations, and that is where expensive surprises tend to hide. A strata-titled property sits inside its own legal and financial structure, which calls for thorough due diligence before you submit any offer.
Begin by pinning down what you would actually own. An apartment purchase typically transfers a unit title or strata title, covering your specific dwelling plus a fractional interest in the common property. Extras such as storage lockers or assigned parking stalls can be separate legal parcels, each requiring its own purchase agreement. Clearing up those boundaries early ensures every functional space you need is secured from day one.
Shared ownership also binds you automatically to the body corporate, known in some places as the homeowners association, or HOA. Members pay regular fees toward building insurance, management salaries, shared utilities, and a long-term maintenance fund. To avoid unwelcome financial burdens down the road, take three steps: review the body corporate’s financial health, check its operating budgets, and read the minutes of past meetings.
Closely linked is the long-term maintenance plan, or LTMP, the hallmark of a well-run building. Before making an offer, examine the reserve fund balances and the schedule of upcoming capital expenditures. A healthy reserve fund signals proactive governance, and it shields owners from sudden, costly special levies for major work such as elevator overhauls or structural remediation.
The building’s master insurance policy deserves equal scrutiny, and reviewing it is non-negotiable. Confirm that premiums are current and that the financial accounts are independently audited on a regular basis. Confirm, too, that the property carries no lingering legal disputes or historical construction defects. Comprehensive coverage protects your investment against unforeseen structural liabilities.
Next come the rules. Community living means following established bylaws, and the body corporate’s rules set the daily operating guidelines, covering pet ownership policies, noise curfews, short-term rental restrictions, and architectural modifications. Study them to make sure your intended lifestyle or investment strategy fits the building’s standards.
Since walls and floors are shared, acoustic engineering becomes a priority. Assess the soundproofing between floors and through adjoining walls to confirm you will have enough privacy. Visiting the complex during peak evening hours or on a weekend gives an authentic read on ambient noise and on the general demographic of the community.
Finally, weigh the age of the building, because age significantly shapes the risk profile. Newer builds offer contemporary aesthetics and energy-efficient systems, but they may hide construction flaws that have not yet surfaced. Older buildings bring proven structural resilience, though they could soon need modernization. A comprehensive evaluation by an accredited property inspector is vital for uncovering hidden maintenance liabilities.
Put the two lists side by side and the shape of the decision is plain. The argument for buying rests on location, affordability, security, amenities, easy upkeep, and efficient use of space. The argument for caution rests on strata ownership, body corporate fees, maintenance planning, insurance, bylaws, noise, and building age. Whether a purchase proves worthwhile may depend on how thoroughly a buyer verifies each of those points before signing, and that homework falls to the buyer.
If this breakdown helped you sort through the decision, hit subscribe so future videos land in your feed as soon as they go live. Tap like if the information was useful, and switch on the notification bell so the latest news and analysis never passes you by.”