Watch the American housing market for a decade, and investors sort themselves into two groups.
One group keeps expanding even when prices fall. The other folds the moment conditions tighten. The people who make it through an entire economic cycle share one trait: they treat real estate as a marathon, and they build a framework before they spend a single dollar.
The first piece of that framework is a defined purpose. It applies whether the opening move is one single-family rental or a multi-market commercial portfolio. The investor needs a long-term strategy that serves as a master blueprint and suits the current economic climate. Buyers without clear goals tend to chase weak deals driven by short-term hype. The goal might be dependable passive income, a large store of home equity, or hard assets passed to future generations. The time horizon then shapes the method. Fix-and-flip tactics depend on market timing and aggressive rehabilitation, while buy-and-hold strategies draw their strength from compound growth, amortization, and slowly rising rents. Concrete milestones keep the plan on track, such as reaching net passive cash flow of three thousand dollars per month within five years.
Next comes the investor’s own financial position, which deserves close study before any listing is opened or any neighborhood comps are reviewed. Building wealth demands a healthy balance sheet, strong creditworthiness, and sensible use of leverage. The budget has to stretch well past the down payment. It must cover closing costs, insurance premiums, and property taxes, plus cash reserves for vacancy periods and capital expenditures such as roof replacements or HVAC upgrades. Lenders reward discipline. A credit score of 740 or higher unlocks the lowest mortgage interest rates, which sharply cuts the long-term cost of borrowing. Outside expertise adds value as well. The recommendation is to hire a certified financial planner and a specialized CPA early, ideally one who knows real estate tax codes, depreciation schedules, and entity structuring through LLCs.
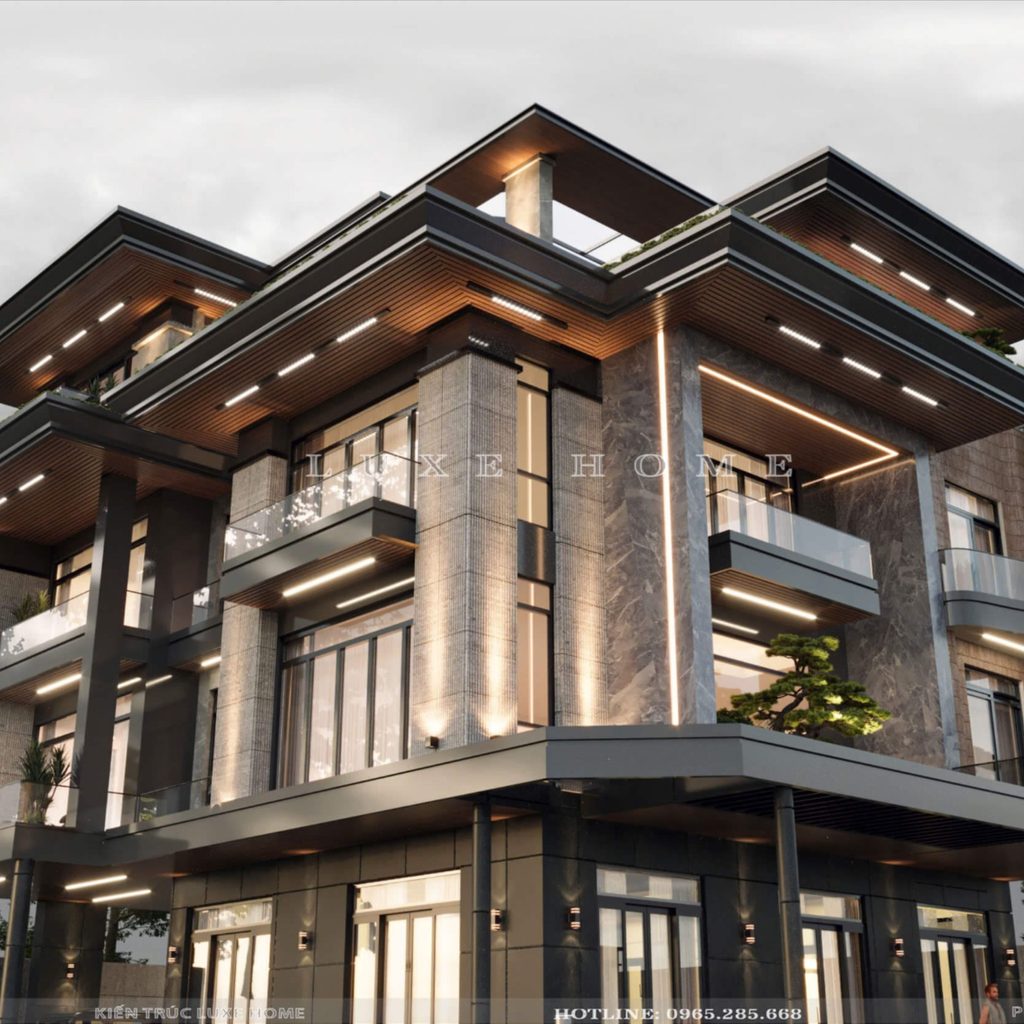
Location, the source says, is the foundation of property performance. Successful investors buy into local economic ecosystems rather than just buildings. Macroeconomic indicators, paired with micro-neighborhood trends, separate a profitable asset from a financial anchor. Employment growth, migration patterns, and local infrastructure projects each merit careful study. Areas that draw corporate headquarters or expanding tech hubs generally show strong rental demand and rising property values. Those findings should be weighed against supply constraints. Where zoning laws or geographic boundaries limit new construction, existing inventory appreciates faster.
Diversification is how investors manage risk. Anyone who puts all capital into one property type or one neighborhood is exposed to a local downturn, so spreading wealth across several dimensions offers protection. The first dimension is asset class. Residential single-family homes or multi-family apartment complexes can be combined with commercial real estate or light industrial space, which captures different yield profiles. The second is geography. Holding assets in different states or metropolitan statistical areas cushions overall returns if one local industry weakens. The third is strategy. Cash-flowing rental assets can operate alongside capital-growth projects, balancing liquidity needs against long-term wealth accumulation.
Daily operations matter just as much, because efficiency directly determines net operating income. As a portfolio grows, owners must decide between managing properties themselves and hiring a professional property management company. Self-management avoids third-party fees but eats up a great deal of time. Professional managers typically charge a percentage of monthly gross rents, and in return they handle tenant screening, lease enforcement, emergency repairs, and legal compliance. Whichever route an owner picks, maintenance should be proactive. Setting aside one to two percent of a property’s value each year for routine upkeep keeps minor wear and tear from turning into costly emergency repairs.
An entry plan with no exit strategy is an incomplete investment thesis. Knowing how and when to divest or transition assets is essential to maximizing cumulative returns. The first option is selling appreciated properties at the peak of a market cycle, then using a 1031 exchange to defer capital gains taxes while rolling equity into larger, higher-performing assets. The second is a cash-out refinance when interest rates are favorable, which taps accumulated equity and frees capital for the next acquisition without triggering a taxable event. The third is estate and succession planning. Working with an estate attorney to set up trusts or pass ownership smoothly to heirs minimizes probate delays and estate tax liabilities.
Taken together, the lesson is that long-term success in real estate goes to those who pair patience with rigorous analysis and a willingness to adapt. Clear goals, a protected balance sheet, intelligent diversification, and planning for every stage of an asset’s life all point toward lasting financial independence. A durable portfolio is built long before the first purchase and carries through to the final transfer. That leaves each investor with one open question: does his or her own plan cover every one of those stages?
If this breakdown gave you something useful, subscribe to the channel so the next report lands right in your feed. Hit the like button to help more viewers find the video, and switch on the notification bell so the latest news and analysis never slips past you.”